
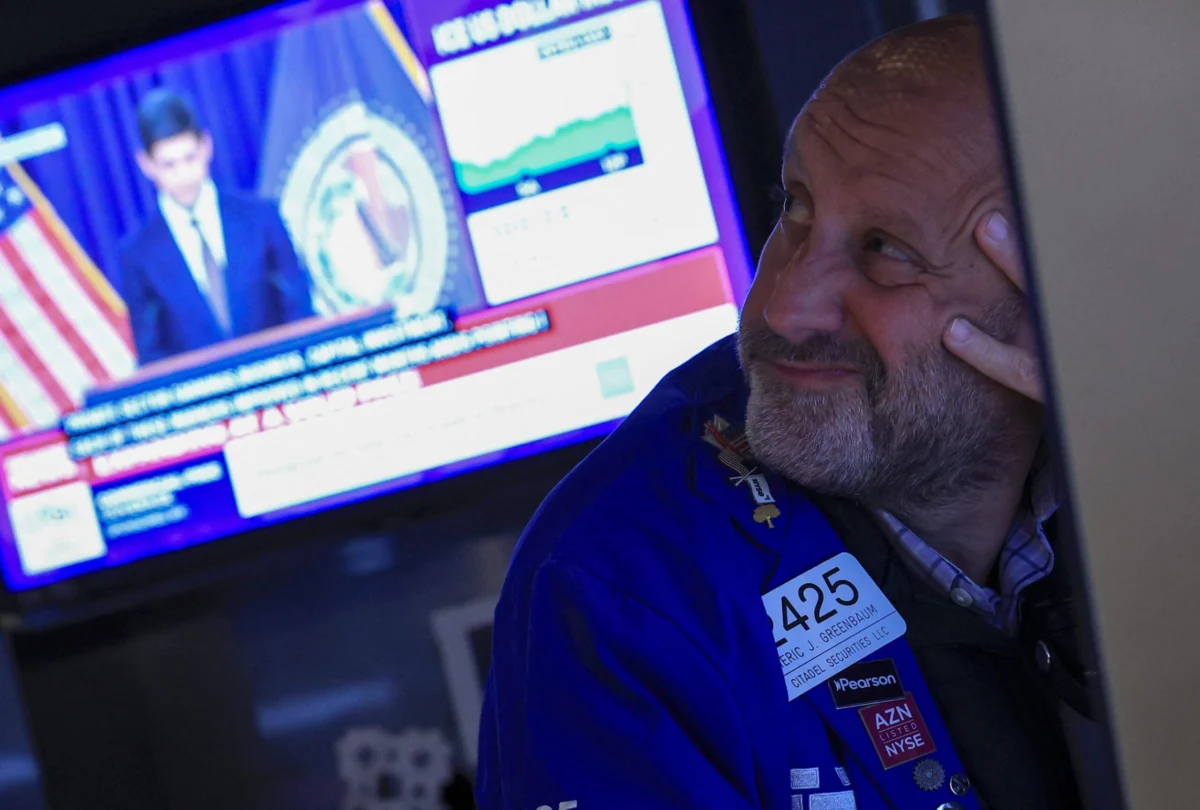
The single most influential benchmark in the global financial architecture has surged to levels not witnessed since the onset of the 2007 financial crisis, leaving Wall Street deeply polarized over whether this milestone signals underlying economic resilience or impending fiscal vulnerability. At the center of this financial tug-of-war is the 10-year U.S. Treasury yield—the foundational interest rate paid by the federal government to borrow capital over a decade, and the baseline upon which nearly every consumer and corporate loan in the United States is priced.
On Friday, the 10-year Treasury yield climbed to 5.21%, sending immediate shockwaves through retail and commercial credit markets. In tandem with this spike, the average rate on a 30-year fixed mortgage jumped to 7.45%. Across the financial ecosystem, automobile loans, credit card annual percentage rates (APRs), and corporate debt issuances are bracing for consequential upward adjustments. This dramatic repricing of debt follows the Federal Reserve’s recent decision to raise its benchmark interest rate—its first monetary tightening move since 2023—in an aggressive bid to cool persistent inflationary pressures. Current market pricing suggests a roughly 70% probability of yet another rate hike at the upcoming Federal Open Market Committee meeting in October.
The upward pressure on yields has been accompanied by a persistent sell-off in government bonds. Highlighting the fragility of current market demand, a recent Treasury auction of five-year notes drew the weakest investor appetite recorded since 2018. Yet, veteran economists and market strategists remain profoundly divided on the root causes of these climbing yields, and more importantly, what they portend for the broader economic horizon.
Decoding the Mechanics of the Bond Market
To understand the gravity of the current economic inflection point, one must examine the fundamental mechanics of sovereign debt. A government bond is, at its core, a formalized IOU. When institutional investors, foreign governments, or retail participants purchase a Treasury security, they are effectively extending a loan to the federal government, which in turn promises to pay regular interest before returning the principal at maturity. The rate of return attached to this loan is the bond yield.
Bond yields operate on an inverse relationship with demand. When fewer market participants are willing to lend capital to the government, Washington must sweeten the deal by offering higher interest rates to attract sufficient buyers. Because commercial lenders peg the pricing of consumer mortgages, auto loans, and corporate credit lines directly to these sovereign benchmarks, the cost of borrowing rises uniformly across the economy.
This dynamic also exerts a gravitational pull on the equity markets. When risk-free government bonds reliably pay upwards of 5%, investors naturally re-evaluate the risk-reward proposition of owning volatile equities. A higher risk-free rate forces stocks to compete harder for capital, frequently resulting in compressed valuations as investors demand greater earnings premiums to justify holding riskier assets.
Long-term bond yields, such as those on 10-year and 30-year Treasuries, price in market expectations regarding the path of monetary policy over extended horizons. If investors anticipate that the Federal Reserve will maintain high interest rates for years to come, they will refuse to lock their money into long-term government debt at a discount, opting instead for short-term instruments that can be continuously rolled over at elevated rates. Furthermore, these yields incorporate the "term premium"—the additional compensation investors demand for the opportunity cost and uncertainty of tying up capital for a decade. Over a ten-year span, myriad macroeconomic risks can materialize, ranging from geopolitical conflicts and inflationary spikes to ballooning national deficits and systemic public health crises.
A Chronology of Monetary Tightening and Market Reaction
The journey toward these multi-decade yield highs has been forged through a distinct sequence of macroeconomic policy shifts and market developments over the past several years:
- 2022–2023: Following historic pandemic-era stimulus programs and supply chain bottlenecks, inflation surges to four-decade highs. The Federal Reserve embarks on its most aggressive monetary tightening campaign in decades, rapidly hiking the federal funds rate from near-zero to a restrictive plateau.
- Late 2023: The central bank pauses its rate-hiking cycle, maintaining a plateau as inflation shows signs of slowing, though core price pressures remain stubborn. Markets begin pricing in anticipated rate cuts for the subsequent year.
- Early to Mid-2024: Artificial intelligence investments trigger an unprecedented corporate capital expenditure super-cycle, keeping corporate balance sheets active and fueling robust economic growth despite high borrowing costs.
- Late 2024: Persistent economic momentum and resilient labor market data force the Federal Reserve to pivot away from anticipated easing. The central bank initiates a fresh rate hike to preemptively cool a resilient economy, pushing short-term expectations higher.
- Recent Weeks: The 10-year Treasury yield breaches 5.21%, a level unseen since 2007. Concurrently, 30-year mortgage rates climb to 7.45%, and a five-year Treasury auction registers the weakest demand since 2018, signaling acute indigestion in the sovereign debt market.
The Case for Boom: Economic Vigor and Technological Super-Cycles
Optimistic market analysts argue that the rise in yields is a byproduct of economic strength rather than structural distress. Proponents of this view assert that the American economy is experiencing genuine, productivity-driven growth, spearheaded by a historic technological revolution.
Chief among these growth engines is artificial intelligence. According to comprehensive data from Goldman Sachs, the largest technological hyperscalers are projected to devote nearly $800 billion to capital expenditures this year, with spending expected to surpass $1.1 trillion by 2027. Economists note that this represents the most intensive tech investment cycle relative to gross domestic product since the dawn of the railroad industry in the nineteenth century.
Because a booming, high-growth economy naturally generates upward pressure on prices, the Federal Reserve is compelled to maintain restrictive monetary policy to keep inflation anchored. In this optimistic framework, investors expect rates to remain elevated because economic profitability is robust enough to sustain them.
Matthew Klein, an esteemed economics commentator and author of The Overshoot newsletter, suggests that the central bank is enacting policy adjustments for fundamentally sound reasons. The economy has exhibited robust performance for years, and policymakers are finally adjusting to a landscape defined by sustained growth and labor market vitality.
Echoing this sentiment, equity analysts at Jefferies argue that mainstream market participants are significantly "underestimating U.S. equities’ ability to absorb longer-term rates." They point to broad-based corporate earnings growth as proof that American corporations can comfortably navigate a higher-for-longer interest rate environment.
The Case for Bust: Fiscal Imbalances and Supply Gluts
Conversely, bearish market participants and fiscal pessimists contend that the current surge in yields is driven less by robust economic health and more by a rapidly rising term premium. This perspective focuses on systemic vulnerabilities and macroeconomic risks beyond the control of monetary authorities.
The primary concern among pessimists is the trajectory of U.S. fiscal policy. Thierry Wizman, a global FX and rates strategist at Macquarie Group, has highlighted Washington’s persistent inability to rein in the federal budget deficit. Furthermore, protracted geopolitical instability—such as the ongoing conflict in the Middle East, which has extended well past its initial phases—has exerted additional pressure on federal expenditures. Every incremental dollar of deficit spending requires the issuance of more Treasury securities, steadily testing the absorption capacity of the global bond market.
Compounding the supply issue is the sheer volume of corporate debt required to fund the aforementioned artificial intelligence boom. Because the capital expenditure outlays of major technology firms currently exceed their available internal cash flows, these corporations are increasingly issuing their own bonds. These corporate issuances directly compete with U.S. Treasuries for a finite pool of investor capital, particularly within an economy where domestic savings rates remain relatively subdued. Wizman warns that without a meaningful deceleration in AI-related spending or a resolution to geopolitical conflicts, sovereign bond yields will remain stubbornly elevated.
Implications for Consumers, Businesses, and Policymakers
The financial implications of a 5.21% ten-year yield permeate every layer of the domestic and international economy. For ordinary consumers, the direct correlation between Treasury yields and mortgage pricing means that homeownership has become significantly more expensive, effectively freezing large segments of the residential real estate market as potential sellers and buyers remain locked into lower legacy mortgage rates. Auto loans and credit card borrowing costs are similarly burdensome, threatening to constrain discretionary consumer spending—the primary engine of U.S. economic activity.
For the corporate sector, higher borrowing costs force CFOs to re-evaluate capital allocation strategies. While mega-cap technology firms with massive cash reserves can self-fund or issue debt against high projected returns, smaller and mid-sized enterprises lacking direct access to capital markets face tightening credit standards and restricted access to growth capital.
As Wall Street continues to debate whether this historic yield milestone heralds a sustainable economic boom or a looming fiscal reckoning, the decisions made in corporate boardrooms and central bank committee rooms over the coming months will dictate the trajectory of the global financial system for years to come.




Leave a Reply