The rapid proliferation of artificial intelligence, high-performance computing, and cloud-based enterprise solutions has catalyzed an unprecedented surge in demand for data center capacity. Across the United States, technology giants and specialized real estate developers have announced billions of dollars in new construction projects intended to house the server farms necessary to power the next generation of AI. However, this gold-rush mentality is increasingly running into the hard, immutable constraints of the physical world. Developers are finding that the distance between a corporate announcement and a fully operational facility is growing, as a confluence of grid instability, local regulatory opposition, and the harsh economic reality of utility interconnection challenges threatens to leave many projects on the drawing board.
The Anatomy of a Cooling Market
The current data center pipeline is characterized by a significant disparity between planned capacity and deliverable infrastructure. While developers continue to publicize massive, multi-gigawatt campuses, industry analysts and energy experts are warning that a substantial percentage of these projects may never reach groundbreaking.
The primary obstacle is not a lack of capital, but a lack of power. Modern AI clusters require an order of magnitude more electricity than traditional web-hosting centers, often demanding hundreds of megawatts in a single location. In many regional markets, the existing electrical infrastructure is simply incapable of supporting this level of load. Consequently, the bottleneck has shifted from real estate acquisition to energy procurement and grid interconnection queues.
Chronology of the Infrastructure Crunch
The trajectory of the current crisis can be traced back to the late 2022 explosion of generative AI, which caught the utility sector unprepared.
- Q4 2022 – Q1 2023: The launch of accessible generative AI tools triggers a massive re-evaluation of compute requirements among hyperscalers. Major firms pivot their capital expenditure strategies toward massive, centralized AI training facilities.
- Q3 2023: Regional Transmission Organizations (RTOs) report a historic spike in interconnection requests. Utilities begin to signal that the time required to upgrade substations and transmission lines is significantly longer than the build-out time for data centers.
- Q1 2024: Concerns regarding grid reliability move to the forefront of state-level policy discussions. Texas, a hub for data center growth, begins to implement stricter auditing requirements for new high-load facilities, citing concerns over the stability of the ERCOT grid.
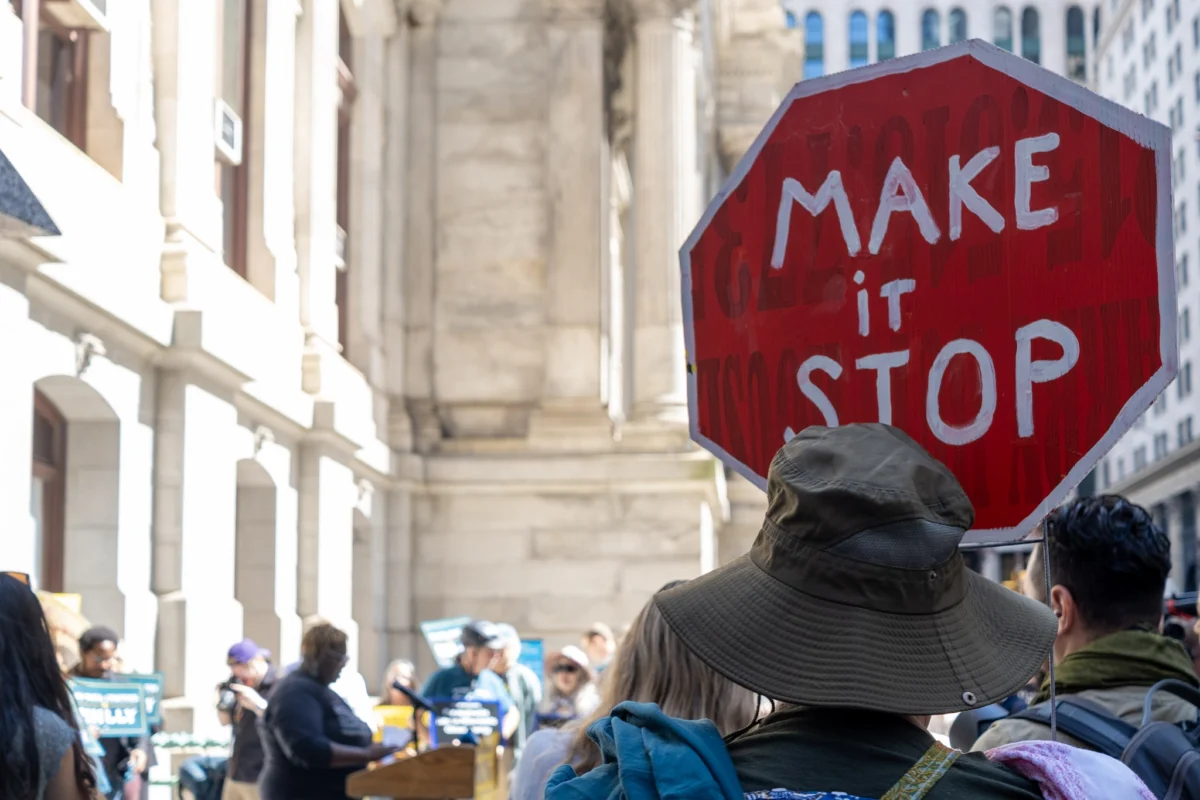
- Q3 2024 – Present: Public resistance to data center development grows in suburban and rural corridors. Local governments, concerned about water usage for cooling and the aesthetic impact of industrial facilities, begin denying zoning permits and blocking land use applications.
The Grid Strain and Power Scramble
The largest constraint on the industry remains the fragility of the U.S. power grid. According to data from the North American Electric Reliability Corporation (NERC), the growth in peak demand from data centers and the electrification of industrial sectors is outpacing the rate of new generation and transmission deployment.
In regions such as Northern Virginia, the global epicenter of data center activity, utilities have already warned that certain areas are "at capacity." This has led to a desperate scramble for alternative energy solutions, including behind-the-meter generation, on-site small modular reactors (SMRs), and long-term power purchase agreements (PPAs) for renewable energy.
However, these solutions are complex. For instance, relying on on-site power generation often triggers a new layer of environmental and safety regulations, while signing large-scale PPAs can exacerbate local energy price volatility for residential and small-business customers. The resulting friction has forced state utility commissions to take a more active role in vetting the long-term feasibility of data center power requests, effectively slowing the permitting process to a crawl.
Distinguishing Speculation from Substantiated Growth
In the context of the Equity podcast, experts like Brent Nelson of Ascend Analytics highlight the necessity of due diligence in identifying "viable" versus "speculative" projects. A project that lacks a signed interconnection agreement or a clear path to water access is, for all intents and purposes, a financial liability rather than a capital asset.
The industry is currently witnessing a "flight to quality" where investors are prioritizing projects that have secured "shovel-ready" status. This includes having:
- Confirmed utility interconnections: Proof that the local substation can handle the requested load without necessitating multi-year grid upgrades.
- Water usage permits: In drought-prone areas, the ability to secure cooling water is as critical as power.
- Community consensus: A lack of organized local opposition, which is increasingly becoming a fatal flaw for massive developments.
Projects that cannot demonstrate these three pillars are now facing significant hurdles in securing debt financing. Lenders are becoming increasingly wary of the "AI hype" cycle, demanding proof of long-term operational feasibility before committing to the capital-heavy construction phase.
Economic and Policy Implications
The cooling of the data center pipeline carries profound implications for the broader economy. If the supply of compute capacity fails to keep pace with demand, the costs of AI development will skyrocket, potentially stifling innovation and slowing the integration of AI into global industries.
From a policy perspective, state and federal governments are beginning to treat data centers as public utility stakeholders rather than private real estate developments. This shift is likely to result in:
- Increased Taxation and Impact Fees: Developers may be required to pay significantly higher costs to offset the burden their projects place on local energy and water infrastructure.
- Stricter Siting Requirements: Zoning laws will likely become more restrictive, pushing data centers toward brownfield sites or areas with surplus energy capacity, such as retired coal-fired power plants.
- Grid Modernization Mandates: Developers may be forced to finance the construction of transmission lines and substations as a condition of their permits, fundamentally altering the return-on-investment profile of new projects.
The View from the Industry
While the challenges are formidable, industry proponents argue that the growth is merely being "rationalized" rather than halted. The high cost of entry and the difficulty of navigating the regulatory landscape are acting as a filter, favoring established hyperscalers and institutional developers who have the capital and the expertise to manage long-term infrastructure projects.
Smaller, speculative developers who entered the market in the early stages of the AI boom are increasingly looking to divest their land and permits, leading to a consolidation of the market. This consolidation is likely to create a more stable, albeit slower, growth trajectory for the sector in the coming years.
Conclusion
The narrative of the "data center boom" is shifting from one of unbridled expansion to one of calculated engineering and political negotiation. The billions of dollars currently earmarked for AI infrastructure will continue to flow, but they will be directed with much higher precision toward projects that can prove their technical and regulatory viability. For investors, policymakers, and industry stakeholders, the next phase of the AI revolution will be defined by the ability to solve the physical constraints of the grid, rather than the ability to simply announce a new facility. The reality check currently underway is not a death knell for the industry, but rather a necessary maturation for a sector that has grown at a pace that the physical world was never intended to sustain.
As the industry moves forward, the focus will inevitably shift toward efficiency—both in terms of power consumption per unit of compute and in the strategic selection of project sites. Those who can navigate the complex web of utilities, local opposition, and regulatory hurdles will define the next generation of digital infrastructure. Those who cannot will likely find themselves holding stranded assets in an era where the constraints of the grid have become the ultimate arbiter of success.