For decades, conventional wisdom in global economics has dictated that a rising superpower inevitably seeks to dethrone the reigning financial hegemon. As China’s economy expanded to become the second-largest in the world, analysts routinely predicted that Beijing would aggressively push the renminbi (yuan) to replace the U.S. dollar as the premier global reserve currency. However, according to recent analysis from prominent international trade and geopolitical scholars, this widely held assumption fundamentally misreads Beijing’s strategic calculus. Far from aspiring to wear the heavy crown of global financial dominance, Chinese leadership actively prefers that the U.S. dollar remain on top, pursuing a much more pragmatic and defensive monetary strategy.
The strategic motivations behind China’s measured approach to currency internationalization were recently outlined by Zongyuan Zoe Liu, a senior fellow for China studies at the Council on Foreign Relations, in a detailed assessment published in Foreign Affairs. Liu argues that assuming the responsibilities of the world’s primary reserve currency would impose unacceptable economic and political costs on Beijing, threatening the very domestic controls that the Chinese Communist Party (CCP) relies upon to maintain political stability.
The Political Risk of Open Capital Markets
To truly replace the U.S. dollar, China would need to fully liberalize its economy by opening its capital markets, allowing the free flow of money across its borders. For Beijing, however, such a move represents an intolerable security risk. Open capital markets would strip the CCP of its tightly guarded oversight regarding who receives capital, how it is deployed, and where it travels.
Furthermore, a fully convertible yuan would undermine a crucial safety mechanism for China’s political and economic elite. Many influential figures within the country rely on offshore dollar holdings as a form of financial insurance against domestic political shifts and potential persecution. By maintaining stringent capital controls, Beijing preserves its domestic grip on power, making the structural sacrifices required for global currency supremacy a non-starter.
Rather than seeking total dominance, China’s primary objective in internationalizing the yuan is defensive: to shield its economy from the weaponization of the U.S.-led financial system. Following the outbreak of the Russia-Ukraine conflict in 2022, Washington and its Western allies swiftly cut Moscow off from the SWIFT global messaging network and froze hundreds of billions of dollars in Russian central bank reserves. That unprecedented economic sanction served as a profound wake-up call for Beijing, highlighting the immense vulnerability of conducting international trade dependent entirely on a U.S.-controlled financial infrastructure.
By establishing a viable alternative currency network—one that is sufficiently internationalized without bearing the burdens of global hegemony—China aims to bypass potential U.S. sanctions. As Liu noted in her analysis, securing a respectable second place, or even a consequential third, is entirely sufficient to break the dollar’s effective monopoly. This approach constrains Washington’s ability to unilaterally impose devastating financial sanctions while sparing Beijing the astronomical economic and administrative efforts required to sustain absolute currency supremacy.
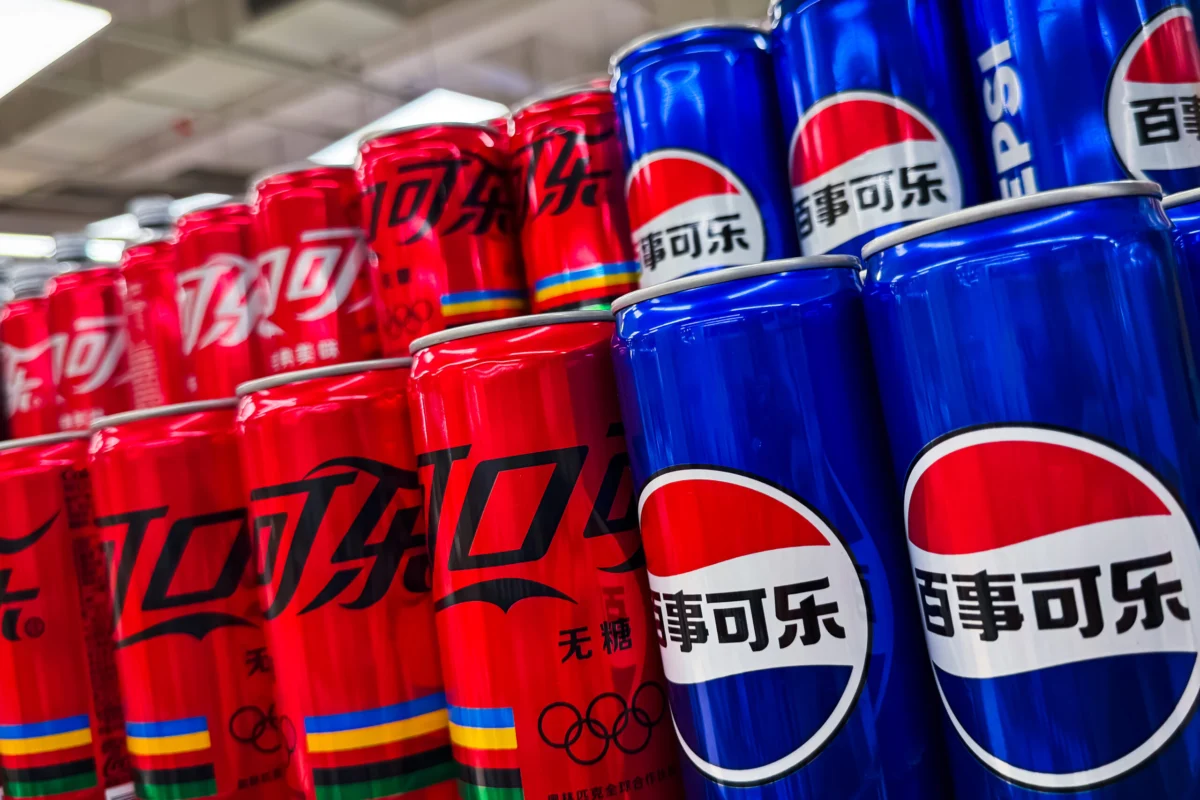
In Beijing’s eyes, the strategic mission is to position the renminbi as the Pepsi to the dollar’s Coca-Cola: never the undisputed market leader, but perpetually serviceable in a pinch and more than capable of keeping the dominant incumbent honest. While the analogy highlights a runner-up status, PepsiCo’s own recent commercial hurdles—such as losing a symbolic contract to replace its soft drinks with Coca-Cola products across thousands of U.S. restaurant locations—underscore the formidable challenge of unseating an entrenched global titan.
Incremental Steps in Global Trade and Finance
Despite its reluctance to shoulder the crown, China has methodically expanded the footprint of the renminbi across international borders. Beijing currently facilitates renminbi usage among corporate entities spanning more than a hundred countries, embedding the currency deeper into a growing array of commodity markets.
Data from mid-year tracking highlights the continuous scaling of China’s financial plumbing. Its proprietary Cross-Border Interbank Payment System (CIPS) boasts nearly 1,900 direct and indirect participants capable of routing transactions smoothly to more than 5,200 financial institutions spread across 191 countries.
Yet, this infrastructure handles only a fraction of the immense volume processed by the U.S.-centric global financial architecture. A truly global currency requires a complete ecosystem encompassing pricing, financing, risk transfer, and reinvestment mechanisms. China has made notable, albeit uneven, progress across these foundational pillars:
- Pricing: Historically, Chinese exporters have invoiced transactions in U.S. dollars, converting them to yuan only upon repatriation. Beijing is actively disrupting this pattern by promoting "China prices"—denominated yuan benchmarks on domestic commodity exchanges. This strategy has already achieved notable success in key industrial inputs like lithium.
- Financing: Chinese state-backed banks have aggressively scaled up their international lending profile, more than doubling yuan-denominated loans to overseas borrowers between 2023 and mid-2026. Simultaneously, the People’s Bank of China has established vital currency swap agreements with 32 foreign central banks and monetary authorities to provide systemic liquidity.
- Risk Transfer: Incremental progress is visible in risk-management markets, with state-owned enterprises beginning to settle maritime cargo insurance using yuan-denominated instruments.
- Reinvestment: This remains the weakest link in Beijing’s monetary chain. A sustainable currency ecosystem requires international recipients to hold and reinvest their renminbi balances rather than immediately converting them into other assets.
While China has gradually expanded foreign institutional access to its domestic stock and bond markets, unpredictable regulatory shifts and stringent capital controls continue to deter foreign investors. Recent statistics illustrate this stark gap: as of March, international investors held a meager 1.6% of the total Chinese bond market, contrasted sharply with a commanding 27% foreign holding rate in the U.S. Treasury market. Without a vastly expanded pool of liquid renminbi assets that foreign entities can buy and sell without friction, the currency cannot mount a realistic challenge to the dollar’s depth and liquidity.
The Rise of the Green Yuan
To circumvent the traditional hurdles of open capital markets, Beijing is attempting to anchor the renminbi’s global utility in a different way—not through petroleum, but through the vital industrial inputs of the clean energy transition. Just as the historic "petrodollar" arrangement anchored the greenback’s dominance in global trade for half a century, China is positioning the yuan to dominate trade in critical minerals, advanced clean energy equipment, and electrical infrastructure.
China has systematically secured dominant control over nearly every segment of the global green technology supply chain, leveraging massive industrial scale and cost advantages that leave Western competitors struggling to catch up. By establishing technological and industrial standards dictated by Chinese-owned firms, Beijing is building the foundation for what analysts term the "green yuan." If China successfully consolidates its monopoly over these hard-to-substitute green exports, it could possess enough structural leverage to price these essential commodities strictly in renminbi, creating a modern equivalent to the petrodollar.
Geopolitical Shocks and the Erosion of the Petrodollar
The urgency of these alternative monetary foundations has accelerated against the backdrop of shifting geopolitical stability in the Middle East. The foundational architecture of the petrodollar dates back to a landmark 1974 agreement, under which Saudi Arabia agreed to price all of its oil exports exclusively in U.S. dollars and reinvest its vast trade surpluses into American financial assets. In exchange for recycling petrodollars back into the U.S. economy, Washington provided a sweeping security umbrella for the kingdom, stationing military personnel in the region, supplying advanced defense hardware, and guaranteeing free navigation through vital maritime chokepoints like the Strait of Hormuz.
However, recent military conflicts in the Middle East—most notably involving extended hostilities with Iran—have severely strained these historical security guarantees and raised profound questions regarding the long-term viability of the petrodollar. Despite weeks of intensive military operations and round-the-clock deployments to protect commercial shipping lanes, the United States has faced persistent challenges in fully restoring safe, unhindered maritime traffic through the Strait of Hormuz.
Concurrently, advanced military tactics utilizing asymmetric drone and missile swarms have inflicted tangible damage on regional infrastructure and military assets, laying bare the limitations of modern air-defense systems in comprehensively shielding Gulf energy facilities.
These security anxieties have not gone unnoticed by regional financial institutions. In a strategic note published in March, analysts at Deutsche Bank warned that ongoing vulnerabilities could prompt Gulf economies to fundamentally unwind their traditional foreign asset savings configurations.
"In this context, reports that the passage for ships through the Strait of Hormuz may be granted in exchange for oil payments in yuan should be closely followed," Deutsche Bank cautioned. "The conflict could be remembered as a key catalyst for erosion in petrodollar dominance, and the beginnings of the petroyuan."
Implications for the Global Financial Order
The convergence of China’s defensive monetary maneuvering, its monopoly over the green energy supply chain, and mounting doubts regarding the reliability of traditional Western security umbrellas in the Middle East suggests that the future of global finance will likely not be bipolar, but multipolar.
Rather than engineering a sudden, disruptive collapse of the U.S. dollar, Beijing is intentionally carving out a parallel financial ecosystem. By providing emerging markets and sanctioned economies with a functional, non-dollar transaction mechanism, China ensures its own economic resilience without inheriting the immense structural obligations of global financial leadership. As the international monetary landscape evolves, the ongoing transformation may well be defined not by the coronation of a new king, but by the quiet rise of a powerful, resilient alternative that permanently alters the balance of global economic power.