
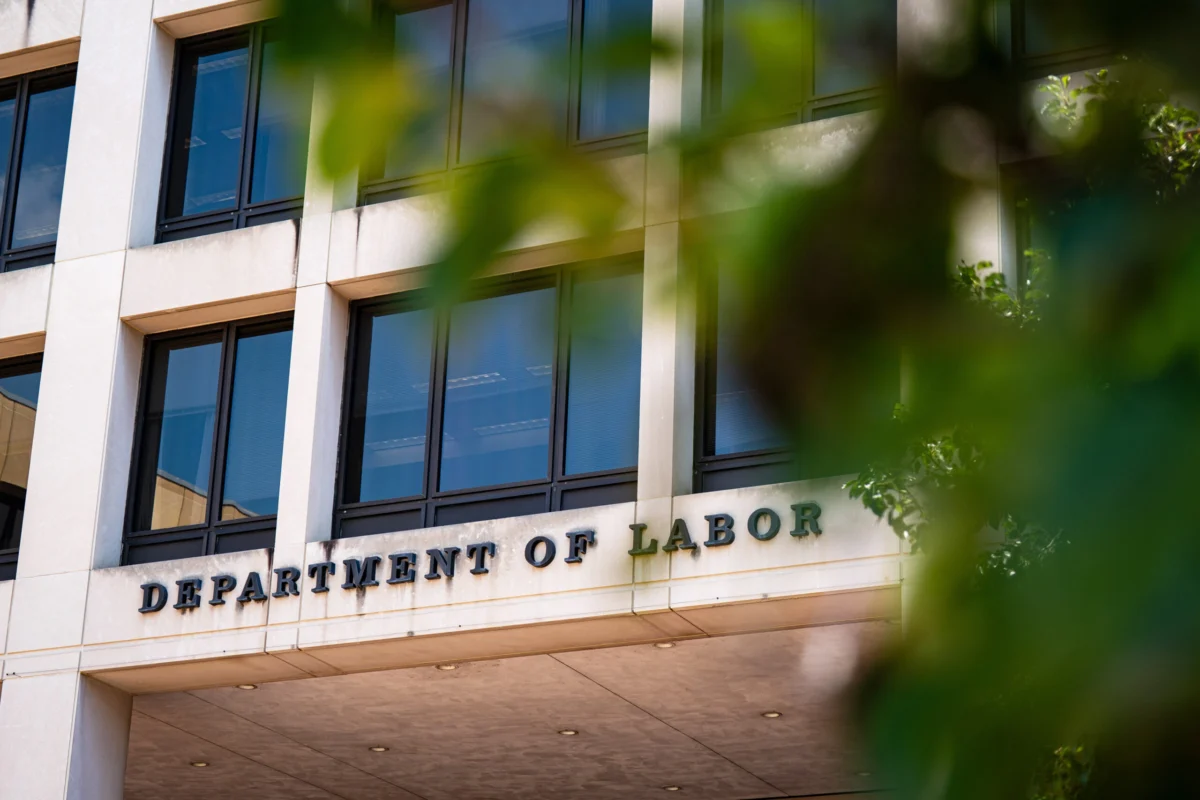
A high-stakes legal battle quietly working its way through the federal court system is drawing intense scrutiny from health policy experts, state regulators, and insurance commissioners nationwide. At the center of the controversy is a multi-year lawsuit pitting Data Marketing Partnership against the United States Department of Labor. While the mechanics of the case sound like an esoteric regulatory dispute over administrative law, its impending resolution could fundamentally redefine the boundary between employee-based benefits and individual health insurance. With court documents signaling that a settlement may be imminent, health economists and consumer advocates are sounding the alarm. If the federal government yields to the plaintiffs, it could open the floodgates to a wave of lightly regulated, lower-cost insurance alternatives that circumvent vital Affordable Care Act consumer protections and strip state regulators of their oversight authority.
The core of the dispute rests on an unusual business model: the "limited partnership" health plan. For consumers navigating a turbulent insurance landscape characterized by surging premiums on Affordable Care Act (ACA) marketplaces, these alternative arrangements often present a tempting pitch. Under models utilized by Data Marketing Partnership and similar entities, individuals can purportedly bypass traditional underwriting hurdles and high ACA premiums. However, the catch is unusual. To qualify for job-based health insurance through the company, consumers must download a specialized software application onto their devices. This application tracks their internet searches, browsing habits, and digital footprints, allowing the parent company to harvest and monetize user data.
For many consumers, the privacy trade-off is a non-starter. But for others—particularly those who earn too much to qualify for federal premium tax credits on ACA exchanges yet find traditional individual market plans prohibitively expensive—the arrangement offers a lifeline to lower-cost coverage. The linchpin of the strategy, however, is legal status: to offer this insurance without complying with state insurance mandates or federal ACA mandates, the company must legally be recognized as an employer, and the data-sharing participants must be classified as bona fide employees or working owners.
The Chronology of a Regulatory Clash
The roots of this conflict stretch back nearly a decade, tracing a winding path through federal agencies, administrative rulings, and appellate courts.
The timeline of the dispute highlights the escalating friction between federal interpretations of labor law and alternative insurance ventures:
- 2019: Data Marketing Partnership files a federal lawsuit against the Department of Labor during the first Trump administration after federal regulators push back against its attempt to classify data-sharing partners as employees for the purpose of offering group health insurance.
- Early 2020: The Department of Labor’s Employee Benefits Security Administration issues a definitive advisory opinion. The agency states unequivocally that individuals who merely download software to capture internet browsing data cannot be considered "employees or bona fide partners" under federal law.
- Late 2020: A federal district court judge in Texas delivers a major blow to the federal government, ruling that the Department of Labor’s advisory opinion was "arbitrary and capricious" and siding with the data-marketing firm.
- 2021: The U.S. Court of Appeals for the 5th Circuit largely upholds the lower court’s pro-business ruling but sends the case back down with instructions to rigorously re-examine whether software users can legally qualify as working owners or bona fide partners.
- 2021–2024: States step into the regulatory void. Insurance commissioners across multiple jurisdictions—including Maryland, Washington, Maine, and Connecticut—issue consumer alerts, levy heavy fines, and issue cease-and-desist orders against various entities offering similar limited-partnership insurance schemes, labeling them unauthorized and financially risky.
- August 2024: A coalition of 19 patient advocacy groups writes a strongly worded letter to the Department of Labor urging continued defense of the agency’s position, warning that a settlement validating these arrangements would dismantle decades of consumer protections.
- Late 2024: Congressional pushback mounts as high-ranking lawmakers warn federal agencies against expanding loopholes that allow misleading call centers to market substandard coverage under the guise of legitimate employment relationships.
- Present: Indications emerge in court filings that a settlement between the Department of Labor and Data Marketing Partnership may be imminent, raising anxieties across the health policy sector.
The Legal Anchor: ERISA and the Regulatory Vacuum
To understand why this lawsuit commands such intense national attention, one must look back to 1974, when Congress enacted the Employee Retirement Income Security Act. Commonly known as ERISA, this landmark federal statute was designed to make it easier for large, legitimate, multi-state employers to manage self-insured health and retirement benefits for their workers without needing to comply with a patchwork of conflicting state-level insurance laws.
Under ERISA, self-insured employer-sponsored plans are largely shielded from state insurance department oversight. They are also exempt from many of the consumer-friendly mandates enforced by the Affordable Care Act, such as the requirement to cover ten categories of "essential health benefits"—including maternity care, mental health services, and prescription drugs—without arbitrary dollar limits.
For decades, this framework served its intended purpose for traditional corporate employers, unions, and multi-state enterprises. However, entrepreneurs and alternative insurance marketers have increasingly sought to exploit ERISA’s structural exemptions. By engineering creative definitions of "employment"—such as downloading a data-tracking app or purchasing a nominal stake in a limited partnership—these entities attempt to cloak themselves in ERISA’s protective armor.
If Data Marketing Partnership succeeds in securing official employer recognition through a favorable settlement, legal and regulatory experts warn it could establish a dangerous legal precedent. The outcome would effectively create a federally sanctioned pathway for any commercial enterprise to set up shop as a pseudo-employer, bundle cheap, limited-benefit insurance with unrelated consumer products or data-harvesting tools, and completely bypass both state insurance commissioners and ACA market rules.
The Ripple Effects on ACA Marketplaces and Insurance Risk Pools
Beyond the technicalities of labor law, health economists point out a profound economic danger: market destabilization. Insurance markets rely fundamentally on broad risk pools, balancing the healthcare costs of sicker, higher-utilizing policyholders against the premiums paid by healthier individuals.
In recent years, Affordable Care Act marketplaces have experienced severe premium hikes, driven in part by declining enrollment among healthy populations who opt out or seek cheaper alternatives. The introduction and potential proliferation of limited-partnership plans threaten to accelerate this adverse selection spiral.
"The only reason why these sorts of products exist is because they aren’t beholden to consumer protection rules of the ACA and can essentially make money by attracting good risk, people who are healthy," explains Ellen Montz, a managing director at Manatt Health and former official who oversaw ACA implementation during the Biden administration.
When healthy consumers are siphoned away by aggressively marketed, low-cost alternatives that offer minimal coverage, the remaining population on ACA exchanges skews older, sicker, and more expensive to treat. The inevitable mathematical result is a vicious cycle of double-digit premium increases, shrinking plan options, and further consumer flight.
State Regulators and Bipartisan Warnings
Opposition to the expansion of limited-partnership insurance spans both political parties when viewed through the lens of state sovereignty and consumer protection. State insurance commissioners, who are tasked with protecting local citizens from fraudulent or insolvent insurance schemes, view the federal lawsuit as a direct assault on their authority.
Ali Khawar, who served as the principal deputy assistant secretary of the Department of Labor’s Employee Benefits Security Administration during the Biden presidency, emphasizes that the issue transcends traditional partisan divisions. "This is not a Republican-Democrat thing," Khawar notes. "It’s really a story about state authority, the way such authority would be significantly undermined in insurance markets."
States have already demonstrated what happens when these alternative arrangements go unchecked. In Maryland, state regulators investigated complaints regarding a company called The Vitamin Patch, which was selling unauthorized limited-partnership health coverage. Finding the entity unlicensed and its products non-compliant, the Maryland Insurance Administration levied fines and ordered operations halted. Similar enforcement actions, consumer warnings, and cease-and-desist orders have been issued by regulatory bodies in Washington, Maine, and Connecticut.
In official state notices, regulators have repeatedly warned that limited-partnership plans often fail to provide comprehensive medical care, leaving vulnerable consumers saddled with catastrophic, unpaid medical bills when they experience unexpected health emergencies. Entities such as the Affiliated Workers Alliance, Consumer Data Partners, Employers Business Alliance, Socios Buenos, and Strategic Limited Partners have all drawn scrutiny from state insurance superintendents for marketing similar self-funded individual products disguised as group plans.
Proponents Argue for Consumer Choice and Affordability
Despite fierce pushback from regulators and patient advocates, proponents of alternative coverage structures maintain that such plans fill a critical market gap. When the Data Marketing Partnership lawsuit was initially filed, attorneys general from several conservative states rallied behind the company, urging the Department of Labor to grant employer status to its limited partners.
Their argument centers on affordability and personal autonomy. Supporters contend that millions of Americans find themselves trapped in a regulatory no-man’s-land: earning too much to qualify for federal subsidies on ACA exchanges, yet priced out of traditional comprehensive health insurance. For these individuals, limited-partnership plans offer a cheaper, albeit bare-bones, option to protect against catastrophic financial ruin—serving, in the view of some conservative policymakers, as an interim marketplace solution.
Proponents have argued that federal oversight through the Department of Labor could establish baseline standards to encourage stable companies to enter the space, and they suggest that market competition ultimately benefits consumers by expanding choices. Furthermore, representatives for Data Marketing Partnership have argued in court filings that denying employer status would force them to terminate health coverage for approximately 50,000 policyholders, simultaneously crippling their ability to attract data-sharing participants and generate business revenue.
The Broader Implications for American Healthcare
As rumors of a potential settlement swirl, patient advocacy groups, state officials, and federal lawmakers are racing to make their voices heard before any deal is finalized. A coalition representing 19 prominent patient advocacy organizations dispatched an urgent letter to the Department of Labor, cautioning that any settlement acknowledging an employer-employee relationship in this context would severely undermine decades of bipartisan work aimed at maintaining stable, transparent, and functional insurance markets.
Concurrently, congressional leaders—including prominent figures on House education and workforce committees—have raised red flags regarding the proliferation of deceptive marketing practices. Lawmakers have highlighted instances where aggressive call centers manipulate consumers into believing they are purchasing comprehensive, traditional health insurance, only to discover they have been enrolled in substandard coverage through a contrived employment scheme.
For policy analysts like Katie Keith of the Georgetown University Law Center, the potential settlement represents a pivotal moment for the nation’s healthcare ecosystem. "Depending on what happens with the settlement, this could be an even bigger expansion," Keith warns. "People are worried that it is the opening salvo into promoting junk plans that don’t meet the ACA requirements."
Ultimately, the resolution of Data Marketing Partnership v. Department of Labor will reverberate far beyond the courtroom. Whether the federal government chooses to defend its long-standing regulatory boundaries or brokers a compromise that legitimizes data-for-insurance business models, the outcome will fundamentally alter the choices available to American consumers—and test the resilience of state-regulated health insurance markets for years to come.




Leave a Reply