
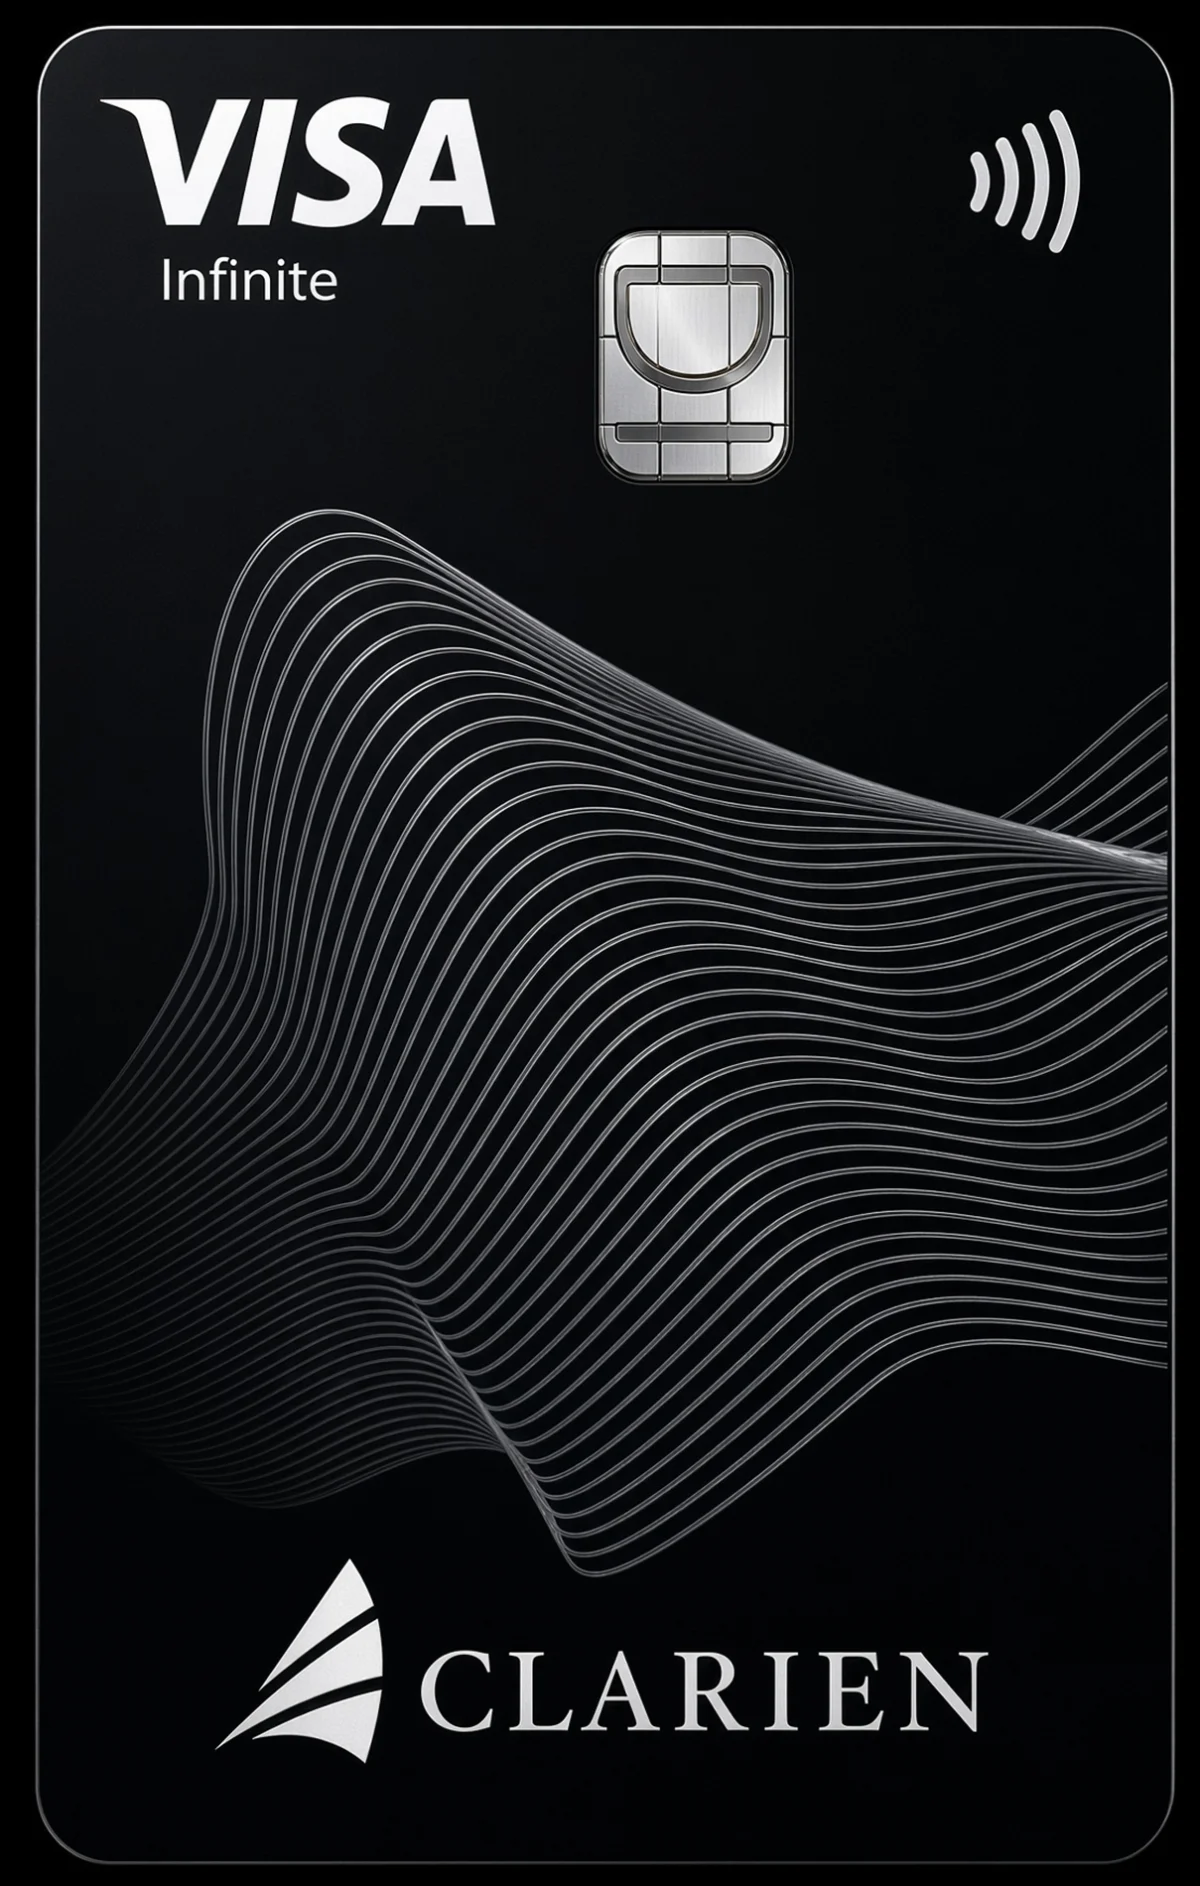
For years, the "Visa Infinite" label served as the gold standard for prestige credit cards, suggesting a ceiling of luxury that could not be surpassed. However, the financial landscape is shifting as both Visa and Mastercard introduce new, even more exclusive tiers that redefine what it means to be a top-tier cardholder. With the introduction of Visa Infinite Privilege and Visa Infinite Private, as well as Mastercard’s debut of World Legend, the industry is moving toward a highly stratified model of wealth management that offers more than just traditional rewards—it offers bespoke lifestyle curation and elevated interchange-funded benefits.
The Shift in Market Hierarchy
The traditional Visa Infinite brand, which launched in the United States over a decade ago, was once the pinnacle of consumer credit. When Chase introduced the Sapphire Reserve in 2016, it utilized the Visa Infinite framework to offer high-end travel perks and protections, partially funded by the higher interchange rates associated with the Infinite designation. However, the global market has long outpaced the U.S. in terms of tiering.
Canada, for example, has been operating under the "Visa Infinite Privilege" model for more than a decade. The rollout of the TD Aeroplan Visa Infinite Privilege in late 2013 signaled a departure from standard premium cards. Today, this tier is ubiquitous in Canada, offering holders tangible advantages like dedicated security lanes at major airports including Vancouver, Ottawa, and Montreal, alongside enhanced parking privileges and exclusive hotel amenities.
In Asia, the evolution is even more pronounced. In July 2026, Visa announced a major overhaul of its Asia Pacific lineup, partnering with institutions like UOB to migrate hundreds of thousands of existing Infinite cardholders into these new, higher-tier categories. This move is not merely cosmetic; it is designed to capture the growing demographic of ultra-high-net-worth individuals who demand a more personalized financial experience.
A Chronology of Premium Tier Development
The timeline of these developments reveals a strategic, gradual migration toward "ultra-premium" offerings:
- 2013–2014: Visa Infinite Privilege makes its debut in the Canadian market with the TD Aeroplan co-branded cards.
- 2015: City National Bank’s Crystal Visa Infinite becomes one of the few available U.S. options, setting the stage for the wider adoption of Infinite-tier cards.
- 2016: Chase elevates the Ritz-Carlton credit card to the Visa Infinite tier, coinciding with the industry-shaping launch of the Sapphire Reserve.
- 2025: Brazil introduces a local iteration of the Infinite Privilege product, which would later be rebranded to align with the global "Infinite Private" standard.
- July 2026: Visa officially launches the refreshed Asia Pacific lineup, introducing Infinite Privilege and the invitation-only Infinite Private tier to markets including Singapore, Thailand, and Vietnam.
- Late 2026: Mastercard gains ground in the United States with the rollout of the "World Legend" tier, effectively positioning itself to compete with Visa’s new ultra-premium offerings.
The Anatomy of "Infinite Private" and World Legend
While "Visa Infinite" remains a widely recognized brand, "Visa Infinite Private" represents an invitation-only experience. According to official documentation, the tier is defined by significantly higher credit limits and the inclusion of a dedicated human concierge. Unlike standard digital assistants, this service is designed to anticipate the user’s needs, such as securing access to private galleries or exclusive clubs that are not available to the general public.

Mastercard, meanwhile, is taking a different approach with its "World Legend" designation. Introduced to provide a clear competitor to Visa’s upper echelons, World Legend benefits currently include specialized airport dining access through the "Taste by Priceless" program. In international hubs like Hong Kong and São Paulo, cardholders gain access to exclusive dining spaces featuring chef-curated menus, a significant step up from standard lounge access. Furthermore, the tier includes pre-booked security fast-track services for the cardholder and up to three guests at participating international airports, as well as lifestyle benefits like complimentary Soho Friends memberships.
Financial Implications: The Interchange Factor
The primary driver behind these tiers is the underlying interchange fee structure. Interchange fees are the costs paid by merchants to the issuing bank for the privilege of accepting credit cards. These fees are generally higher for premium and ultra-premium cards, as they provide the revenue necessary to fund the expensive perks—such as free hotel nights, high-tier status in loyalty programs, and personalized concierge services—that characterize these cards.
Data from the Canadian market illustrates this clearly. For standard consumer credit, the electronic interchange rate for a Visa Infinite card is approximately 1.57%. By contrast, the rate for a Visa Infinite Privilege card sits at 2.08%. When moving to "card-not-present" transactions, the gap widens further, with Privilege cards commanding rates as high as 2.40%. This differential is the engine room of the ultra-premium market; it allows issuers to offer substantial value to cardholders while maintaining healthy profit margins for both the bank and the payment network.
Competitive Analysis and Market Strategy
The strategy employed by Visa and Mastercard is twofold: retention and segmentation. By creating new tiers like Infinite Private and World Legend, banks can better segment their client base. High-net-worth individuals who were once satisfied with a standard Infinite or World Elite card are now being incentivized to upgrade, which keeps them locked into the issuer’s ecosystem.
However, a recurring issue remains the inconsistency of benefits across different regions. For example, the Banyan Group free hotel night offer, which provides "Voyager" status and access to high-value villas, is currently restricted to Asia-Pacific issued cards. Similarly, while Canadians enjoy priority security lanes, these benefits are not universally replicated for U.S. cardholders of similar tiers. This suggests that while the "brand" of the card is global, the "value proposition" remains localized to the specific banking regulations and merchant agreements of each region.
The Future of Ultra-Premium Banking
As we look toward the remainder of the decade, the trend of tier expansion is likely to continue. The move from "Infinite" to "Private" or "Legend" signifies a shift in the role of the credit card. It is no longer merely a payment device; it is a lifestyle management tool.
For the consumer, the impact is a more tailored experience, but also a more complex one. The proliferation of tiers means that the consumer must be increasingly vigilant about which card offers the best utility in their specific region. For merchants and the financial industry, the rise of these tiers signals a permanent increase in the cost of accepting payments from high-spending consumers. As the competition between Visa and Mastercard intensifies at the very top of the wealth pyramid, the definition of "premium" will continue to evolve, likely leaving the standard Infinite and World Elite tiers as the new "entry-level" options for the affluent consumer, while the true elite migrate to the exclusive, invitation-only offerings that define the next generation of global finance.




Leave a Reply