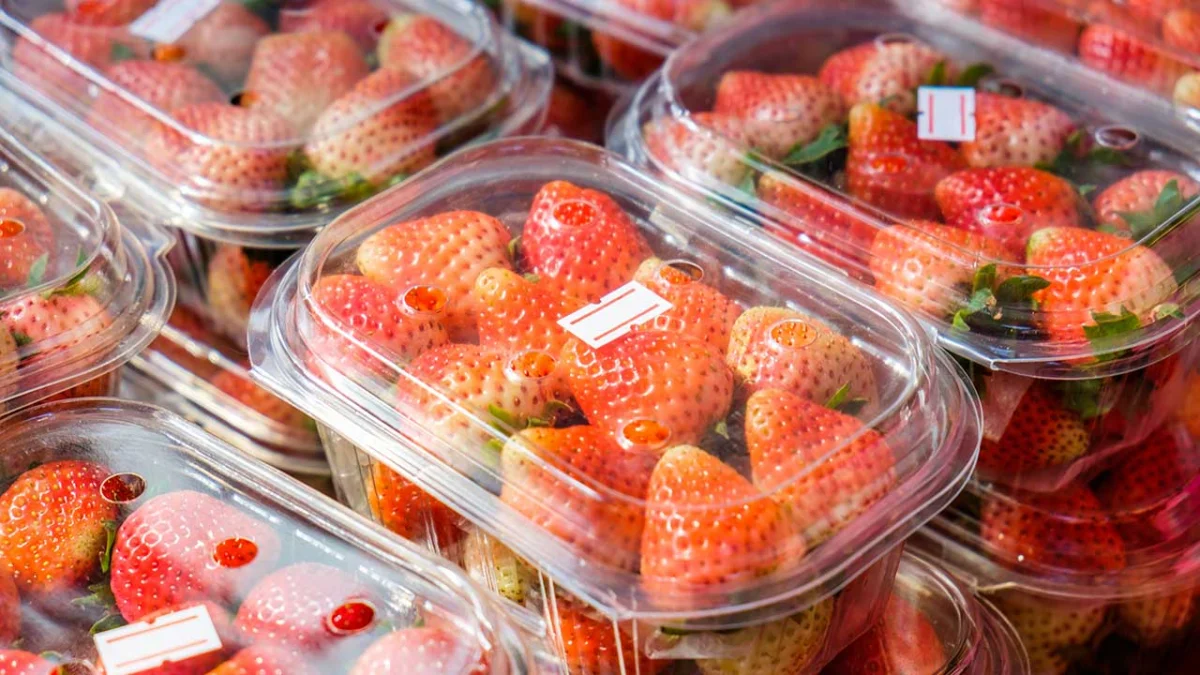
By 2028, the mundane act of grocery shopping will undergo a quiet but radical transformation. Consumers will find fruits encased in sturdy cardboard instead of traditional plastic clamshells, takeout salads served in fiber-based bowls, and microwaveable meals packaged in clear or white trays that have finally shed the opaque, non-recyclable black plastic of the previous decade. These shifts are the tangible, physical manifestations of California’s landmark Senate Bill 54 (SB 54), a piece of legislation that has fundamentally rewritten the rules for how consumer goods are packaged and processed in the United States. Following the finalization of regulations in May 2026, the state began a multi-year transition toward a circular economy, mandating that all single-use packaging sold within its borders must be demonstrably recyclable or compostable by 2032.
The significance of SB 54 extends far beyond the California coastline. Because major multinational corporations prefer standardized packaging processes to reduce costs, they are increasingly adopting these stringent California requirements as their new global baseline. Rather than maintaining dual supply chains—one for the California market and one for the rest of the world—manufacturers are reformulating their containers to meet the highest common denominator, effectively turning California’s environmental policy into a de facto national standard.
The Crisis of Plastic Waste and the Shift to EPR
To appreciate the necessity of this transition, one must look at the staggering scale of the plastic waste crisis. For decades, the convenience of plastic—its low weight, durability, and cost-effectiveness—made it the industry standard for everything from electronics to fresh produce. However, this convenience came with a mounting environmental cost. According to data from the U.S. Environmental Protection Agency (EPA), plastic waste accounted for a mere 0.4% of municipal solid waste in 1960. By 2018, that figure had surged to 12.2%, reflecting a massive, unchecked growth in synthetic material disposal. Research from the advocacy group Greenprint suggests that while 36% of all manufactured plastic is dedicated to packaging, a dismal 85% of that material ultimately finds its way into landfills rather than recycling facilities.
The core mechanism designed to arrest this trend is Extended Producer Responsibility (EPR). Historically, the financial and logistical burden of managing plastic waste fell squarely on the shoulders of taxpayers and local municipal governments. EPR flips this model entirely, placing the fiscal responsibility for waste management on the companies that manufacture and sell the packaging. By forcing producers to internalize the costs of end-of-life disposal, SB 54 creates a powerful financial incentive for corporations to simplify their packaging, reduce the total volume of material used, and steer clear of problematic chemicals and non-recyclable resins.
Chronology of Regulatory Milestones
The implementation of SB 54 is structured around a rigorous, multi-year roadmap intended to give producers time to adjust while maintaining steady progress toward sustainability.
The process began in earnest on May 1, 2026, when permanent regulations took effect. By June 1, 2026, producers were required to register with the Circular Action Alliance or formally declare their status with CalRecycle. January 1, 2027, marks the start of the full program implementation, requiring that single-use plastic packaging be reduced by at least 10% below the 2023 baseline.
As the program matures, the targets become significantly more aggressive. By January 1, 2028, the law requires that 30% of all covered single-use plastic packaging must actually be recycled, moving the metric from "recyclability" (the potential to be recycled) to actual throughput. By 2030, this recycling target increases to 40%, accompanied by a 20% mandate for source reduction. The final milestone, set for January 1, 2032, requires a 65% recycling rate and a total reduction of 25% in plastic packaging volume.
Industry Challenges and Legal Pushback
The transition has not been without controversy. On June 2, 2026, a coalition of environmental organizations—including Oceana, the Natural Resources Defense Council (NRDC), and the Californians Against Waste Foundation—filed a lawsuit in the San Francisco Superior Court. The plaintiffs argue that the final regulations adopted by state agencies contain significant loopholes. Specifically, the suit contends that the regulations provide overly broad exclusions for certain categories of plastic packaging, allow producers to claim indefinite exemptions, and fail to sufficiently restrict emerging technologies that the law was originally intended to curb.
Industry representatives, meanwhile, have expressed concerns regarding the logistical and financial hurdles of meeting such aggressive targets within a six-year window. The cost of upgrading municipal material recovery facilities (MRFs) to handle more diverse material streams is substantial, and the burden of these investments is ultimately passed through the EPR fee structure to the producers.
Packaging Materials Under Scrutiny
Several specific categories of plastic are currently being phased out or redesigned to align with the new regulatory reality:
- Polystyrene Foam: Often referred to by the brand name "Styrofoam," expanded polystyrene (EPS) is notoriously difficult to recycle. It is lightweight, primarily composed of air, and prone to breaking into micro-fragments that contaminate other recyclables. California has already prohibited the sale and distribution of EPS food service ware, pushing industry leaders toward molded fiber and cardboard alternatives.
- Black and Dark-Colored Plastics: Many recycling facilities utilize near-infrared (NIR) optical sorters to identify and separate plastics. These sorters rely on light reflection to categorize materials; however, the carbon black pigments used in dark packaging absorb this light, rendering the items invisible to sensors. Consequently, these items are frequently rejected and sent to landfills. Expect to see a shift toward clear or light-colored PET plastic, which is easily identified by current sorting infrastructure.
- Polyvinyl Chloride (PVC): Commonly found in clear blister packs and rigid clamshells, PVC is a major contaminant in the PET recycling stream. Even small amounts of PVC can compromise an entire bale of recycled plastic. Under SB 54, producers are being pushed to switch to rPET (recycled PET) or fiber-based solutions.
- Oxo-Degradable Plastics: These materials, which are often marketed as "degradable" or "eco-friendly," are essentially conventional plastics infused with additives that accelerate fragmentation. Rather than truly biodegrading, they break down into microplastics, exacerbating pollution. The law effectively bans these, emphasizing the need for materials that meet verified compostability standards.
Broader Economic and Behavioral Implications
The ripple effect of California’s policy is already influencing other states. Oregon’s Recycling Modernization Act and similar legislative efforts in states like Colorado, Maine, and New York indicate a growing regional trend toward EPR. As companies struggle to navigate a "patchwork" of state regulations, the logical business response is to adopt a unified strategy that meets the most stringent requirements—California’s—across all markets.
This legislative pressure is forcing a behavioral shift in how products are sold. We are already seeing an increase in pilot programs for refillable containers, concentrated cleaning pods that reduce the need for shipping water weight, and in-store bulk dispensing systems. These innovations not only reduce the physical volume of packaging but also signal a fundamental change in the consumer experience.
Consumer Advocacy and the Role of Transparency
While the heavy lifting of compliance falls on producers, consumers play a vital role in the transition. The rise of "greenwashing"—where companies use vague marketing terms like "earth-conscious" or "naturally degradable" without third-party verification—remains a significant risk. Experts advise shoppers to look for standardized certifications, such as the Biodegradable Products Institute (BPI) logo for compostables or the How2Recycle label for clear disposal instructions.
Furthermore, the efficacy of the law depends on the health of local recycling infrastructure. Recyclability is inherently local; a container that is technically recyclable may still end up in a landfill if the local municipal facility lacks the equipment to process it. Consequently, the funds generated by EPR fees are earmarked for upgrading this essential infrastructure. By investing in robotics, optical sorting, and industrial composting, the state aims to transform the current linear "take-make-waste" model into a circular system where materials are kept in constant use.
Looking toward 2032, the ultimate goal is to move beyond mere compliance toward a system where packaging is intentionally designed for a second, third, and fourth life. While the path to a 65% recycling rate is fraught with technical and logistical challenges, SB 54 represents the most significant legislative intervention in the history of U.S. consumer packaging. For the American shopper, the coming years will be defined by a shift toward clarity, durability, and a renewed focus on the life cycle of every container that crosses the threshold of their home.