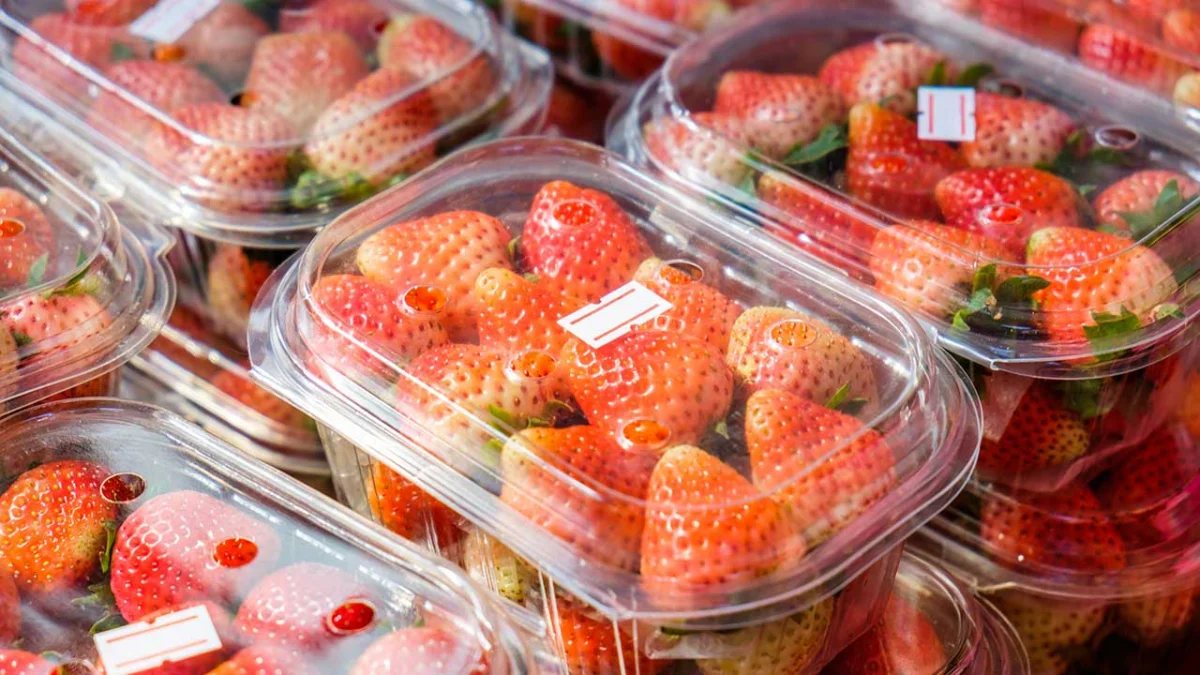
By 2028, the mundane act of grocery shopping will undergo a quiet but profound transformation. Consumers will find that the familiar clamshell containers housing fresh berries have been replaced by fiber-based boxes, and the ubiquitous black plastic trays used for microwaveable meals have given way to clear or white alternatives. These modifications are not merely aesthetic choices by retailers; they represent the tangible, physical manifestations of California’s Senate Bill 54 (SB 54), a piece of landmark legislation that fundamentally redefines the relationship between product manufacturers and the waste they generate.
The Plastic Pollution Producer Responsibility Act, which saw its final regulations take effect in May 2026, serves as a watershed moment for environmental policy in the United States. By shifting the financial burden of waste management from the public sector to the private sector, the law aims to address the staggering environmental crisis caused by single-use plastics. As major manufacturers look to streamline their supply chains, these changes are expected to transcend California’s borders, effectively creating a de facto national standard for packaging design.
The Legislative Framework: A Shift in Accountability
At the heart of SB 54 is the concept of Extended Producer Responsibility (EPR). For decades, the cost of managing the end-of-life cycle for packaging—collection, sorting, and disposal—fell squarely on the shoulders of taxpayers and local municipal governments. Under the new regulatory framework, that liability shifts to the producers themselves. Companies that sell packaged goods in California are now required to join a Producer Responsibility Organization (PRO), such as the Circular Action Alliance, to fund and manage the recovery of their packaging.
This shift creates a direct financial incentive for corporations to reduce their reliance on problematic materials. If a company uses packaging that is difficult or expensive to recycle, they face higher fees. Conversely, by adopting materials that are easily processed by existing sorting infrastructure, manufacturers can reduce their operational costs. The law’s primary objectives are ambitious: a 25% reduction in single-use plastic packaging by 2032 and a mandate that all single-use packaging sold in the state must be proven recyclable or compostable.
The Environmental Context: Why the Urgency?
The urgency of SB 54 is underscored by decades of unchecked growth in plastic production. Data from the U.S. Environmental Protection Agency (EPA) highlights a concerning trajectory; in 1960, plastic accounted for a negligible 0.4% of municipal solid waste. By 2018, that figure had ballooned to 12.2%. Packaging is the primary driver of this trend, accounting for approximately 36% of all manufactured plastic. Most alarmingly, roughly 85% of this material ends up in landfills, representing a massive loss of resources and a significant environmental burden.
Environmental advocacy groups, however, argue that the implementation of SB 54 is still a work in progress. On June 2, 2026, a coalition including Oceana, the Natural Resources Defense Council (NRDC), and the Californians Against Waste Foundation filed a lawsuit in the San Francisco Superior Court. The plaintiffs contend that the finalized regulations contain excessive exclusions for large categories of plastic packaging and permit producers to claim indefinite exemptions, potentially undermining the law’s original intent to curb plastic pollution.
Targeted Materials and Redesign Challenges
The legislation targets specific materials that have historically hindered recycling efficiency. Among the most significant changes is the phase-out of expanded polystyrene (EPS) food service ware. Often referred to as "Styrofoam," EPS is notorious for its inability to be recycled effectively. Because it is largely composed of air, it is prohibitively expensive to transport and prone to breaking into small, unrecoverable fragments that contaminate streams of higher-value plastics.
Similarly, the industry is moving away from "carbon black" plastic. Many optical sorters at recycling facilities utilize near-infrared (NIR) light to identify plastic types. Because the carbon black pigment absorbs this light, these trays remain invisible to sensors and are discarded as waste. Replacing these with clear or white polyethylene terephthalate (PET) allows for higher recovery rates, aligning with the circular economy goals of the state.
PVC-based clamshells and blister packs face similar scrutiny. As a major contaminant in the PET recycling stream, even small amounts of PVC can ruin entire batches of recyclable material. Furthermore, the additives required to make PVC flexible—such as phthalates—have raised significant public health concerns, linking them to chronic conditions such as infertility and diabetes.
A Chronology of Compliance
The transition mandated by SB 54 is structured in stages, allowing manufacturers time to pivot their manufacturing processes.
- May 1, 2026: Final regulations take effect. Producers are required to register with the Circular Action Alliance or file as independent producers with CalRecycle.
- January 1, 2027: Full program implementation. Producers are mandated to achieve a 10% reduction in single-use plastic compared to the 2023 baseline. Mitigation fund payments commence.
- January 1, 2028: The recycling rate target reaches 30%. Packaging must not only be technically recyclable but effectively recycled.
- January 1, 2030: Recycling rate targets rise to 40%, with a 20% reduction in source materials.
- January 1, 2032: The final milestone: 100% of covered packaging must be recyclable or compostable, with a 65% recycling rate and a 25% total reduction in plastic volume.
Broader Economic and National Implications
The influence of SB 54 extends far beyond California’s geography. In a globalized market, companies are unlikely to produce one version of a product for California and another for the rest of the nation. The cost and logistical complexity of maintaining dual supply chains act as a forcing function, compelling manufacturers to adopt the stricter California standards nationwide.
This has already triggered a "patchwork" effect of legislation across the country. States like Colorado, Maine, Oregon, and Washington have either passed or are actively debating their own versions of EPR legislation. This momentum is slowly filling the void left by the absence of a comprehensive federal framework for packaging. As regional standards begin to harmonize—particularly on the West Coast—national brands are finding that the "California standard" is becoming the most efficient way to maintain market access across the U.S.
The Greenwashing Risk
As manufacturers scramble to align with these new requirements, consumers should remain vigilant against "greenwashing." Vague marketing terms like "eco-friendly" or "earth-conscious" often lack scientific rigor. The rise of "bioplastics" presents a specific challenge; while these materials are plant-based, they do not automatically degrade in natural environments. Many require industrial composting facilities to break down, and some have been found to contain chemical additives that may cause environmental toxicity.
Experts recommend that consumers look for third-party certifications, such as the Biodegradable Products Institute (BPI) logo for compostability or the "How2Recycle" label for clear disposal instructions. These standards provide a baseline of transparency that generic marketing claims cannot replicate.
The Road to a Circular Economy
The long-term vision of SB 54 is the creation of a circular economy where waste is designed out of the system at the source. This involves not only changing materials but rethinking business models. We are already seeing the early stages of this transition: the introduction of refillable cleaning stations, the use of concentrated pods that eliminate the need for single-use plastic bottles, and a shift toward reusable container programs in the food service industry.
The revenue generated from EPR fees is intended to be a catalyst for this change. By funneling millions of dollars into infrastructure, the state aims to upgrade material recovery facilities (MRFs) with advanced robotics and optical sorting technology. This investment is crucial; without the ability to process these materials at scale, the goal of a 65% recycling rate will remain out of reach.
For the average consumer, the role is evolving from passive user to active participant. By prioritizing products with minimal, recyclable, or reusable packaging and supporting brands that show genuine commitment to these standards, the public can help accelerate the market shift. While the transition will undoubtedly present challenges—such as initial price adjustments and changes in product availability—the shift represents a necessary evolution in how society manages its consumption. As the 2032 deadline approaches, the success of SB 54 will serve as a bellwether for whether the United States can effectively transition toward a more sustainable, circular industrial future.