
The Scope of the Proposal and Regulatory Timeline
The announcement, released earlier this month, seeks to codify a strict interpretation of federal tax law as it pertains to charitable organizations. If finalized, the rule would apply to approximately 18,000 private schools and colleges across the United States. The regulatory process began with a notice of proposed rulemaking, which triggers a period of public comment. Following this window, the Treasury Department and the Internal Revenue Service (IRS) will review feedback before determining whether to move forward with a final rule.
The proposal arrives in a complex legal climate following the 2023 Supreme Court decision in Students for Fair Admissions v. Harvard, which restricted the use of affirmative action in higher education. While that ruling focused primarily on constitutional protections under the Fourteenth Amendment, the Treasury proposal aims to tighten the fiscal leash on private institutions by leveraging the tax code. Under current Internal Revenue Code standards, educational institutions must operate for charitable purposes to maintain tax-exempt status. The new rule would explicitly define the consideration of race in institutional operations as inconsistent with these requirements.
Economic Implications for Vulnerable Institutions
For private institutions, the loss of tax-exempt status is not merely a bureaucratic hurdle; it is a potential existential threat. The financial model of American private higher education relies heavily on the tax-deductibility of private donations. If the Treasury proposal is enacted, donors would no longer be able to deduct contributions to these institutions, which would likely lead to a significant contraction in philanthropic support.
Furthermore, the institutions would face the prospect of paying federal taxes on investment income, a change that could evaporate the endowments that fund student scholarships and campus infrastructure. Many smaller, tuition-dependent colleges already operate on razor-thin margins. Analysts suggest that the loss of tax-exempt status could force the closure of programs, the termination of faculty, and, in extreme cases, the total cessation of operations for institutions that lack the deep capital reserves of elite universities.
A Historical Perspective on Minority-Serving Institutions
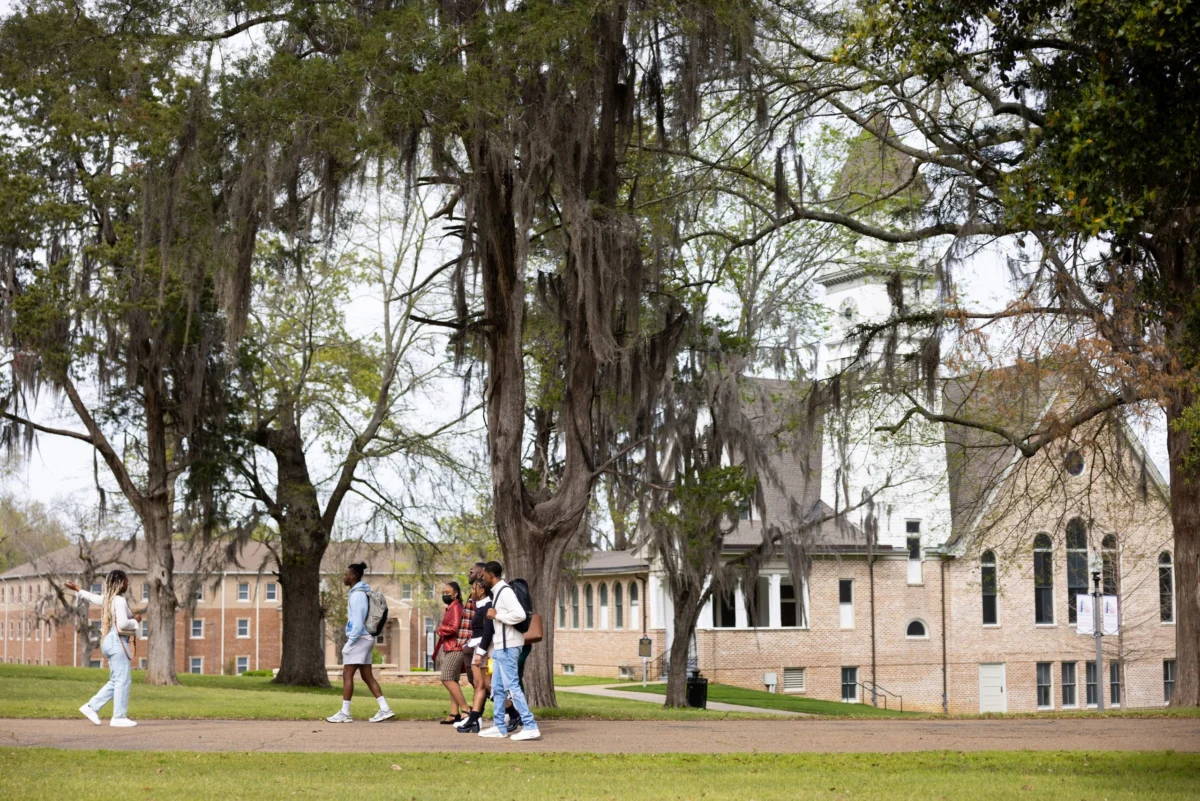
The proposal’s impact is poised to fall disproportionately on Historically Black Colleges and Universities (HBCUs), Tribal Colleges and Universities (TCUs), Hispanic-Serving Institutions (HSIs), and faith-based colleges. Critics of the proposal argue that these institutions were created precisely because the broader American education system intentionally excluded the populations they now serve.
Historically, the mission of an HBCU, for instance, has been to foster academic excellence within a specific cultural and historical context. During the early 20th century, when American academia was rife with exclusionary quotas—most notably those targeting Jewish students and scholars—many HBCUs served as sanctuaries. Records indicate that at least 51 European refugee scholars, many of whom were Jewish, were hired by 19 different HBCUs after being barred from mainstream white institutions. This historical precedent highlights a fundamental misunderstanding in the current Treasury proposal: the difference between exclusionary discrimination and inclusive mission-driven recruitment.
Fact-Based Analysis of Equity-Based Programming
The Treasury Department’s directive conflates "race-conscious" programs with "preferential treatment," yet there is a clear distinction in pedagogical and administrative practice. Many private colleges maintain support programs, such as specialized academic advising for first-generation students or targeted outreach in STEM fields for Native American students, to address tangible disparities in student outcomes.
Data from the National Center for Education Statistics (NCES) consistently demonstrates that first-generation, low-income, and minority students face systemic barriers to college completion. Programs designed to support these students are often the primary driver of retention and graduation for these cohorts. If these programs are stripped of their institutional backing to avoid federal tax penalties, the institutions will be forced to abandon the very work of "closing the gap" that many of them were founded to perform. The resulting policy would, in effect, punish institutions for attempting to rectify the structural imbalances that the federal government itself has documented for decades.
Reactions from the Higher Education Community
While the Treasury Department maintains that the rule is necessary to ensure uniform compliance with federal anti-discrimination laws, leaders in higher education have voiced significant concern. Associations representing private and minority-serving colleges argue that the move ignores the nuance of institutional missions.
"The goal of expanding access should not be conflated with prohibited discrimination," noted one policy analyst familiar with the ongoing discussions. "There is a profound difference between a system designed to keep people out and an initiative designed to bring people in who have been historically pushed to the margins."
Supporters of the Treasury’s move, however, argue that the government has a responsibility to ensure that no institution receiving tax benefits is engaging in race-based decision-making. They contend that a colorblind approach to tax policy is the only way to ensure fairness across the board, regardless of an institution’s historical mission or the demographics of its student body.
The Broader Implications for Future Enrollment
The long-term consequences of this policy shift could fundamentally alter the landscape of American higher education. If the proposal is finalized, colleges may become paralyzed by legal uncertainty. The risk of losing tax-exempt status could lead to a "chilling effect," where institutions proactively dismantle all initiatives involving race, even those that are legally defensible, to avoid the scrutiny of the IRS.
This could lead to a decline in diversity at private institutions, as scholarship programs that currently bridge the gap for students from marginalized backgrounds are scaled back or eliminated. As fewer students from diverse backgrounds are able to access these institutions, the demographic composition of the American workforce could shift, potentially impacting industries that rely on a diverse pipeline of college-educated professionals.
Conclusion: The Tension Between Policy and Reality
The Treasury Department’s proposal stands at the intersection of a complex legal landscape and the deeply rooted mission of American education. By attempting to impose a singular standard on a diverse array of 18,000 institutions, the government faces a challenge in balancing the need for broad non-discrimination policies with the reality of institutional history and the necessity of targeted support for underserved students.
As the comment period progresses, the debate is expected to intensify. The ultimate outcome of this proposal will likely be determined by whether the administration can craft a regulatory framework that addresses genuine instances of discrimination without dismantling the institutional mechanisms that have, for over a century, expanded the doors of opportunity to those whom the rest of the system had forgotten. The decision will have lasting impacts not only on the bottom lines of thousands of private colleges but on the future of social mobility and academic equity in the United States. Whether this policy ultimately serves to promote equality or merely hinders the efforts of institutions trying to solve persistent educational disparities remains the central question facing the sector today.




Leave a Reply