
The Regulatory Framework and Its Scope
The proposed rule would fundamentally alter the tax landscape for as many as 18,000 private educational institutions across the United States. Under current federal law, these schools benefit from tax-exempt status, which allows them to accept tax-deductible charitable donations and exempts their investment income from federal taxation. The Treasury Department’s proposal argues that any school utilizing race as a factor in admissions, financial aid, or athletic recruitment acts in violation of the public policy mandates required to maintain 501(c)(3) status.
If finalized, the impact on the financial viability of these institutions would be profound. Financial analysts and higher education advocates warn that the loss of tax-deductibility for donors would lead to a sharp decline in philanthropic support, which serves as a critical revenue stream for many small and medium-sized private colleges. Furthermore, the imposition of federal taxes on institutional endowments and investment income would likely force severe budgetary contractions, resulting in the elimination of academic departments, the reduction of campus facilities, and potential institutional closures.
Chronology of Federal Oversight and Judicial Precedents
The current proposal does not exist in a vacuum; it is the latest development in a long-standing tension between federal tax policy and institutional mission. The legal foundation for taxing discriminatory schools dates back to the 1983 Supreme Court case Bob Jones University v. United States, which affirmed the IRS’s authority to deny tax-exempt status to private schools that practice racial discrimination.
In recent years, the legal landscape shifted dramatically following the Supreme Court’s 2023 decision in Students for Fair Admissions v. Harvard. That ruling effectively ended race-conscious admissions practices at public and private universities receiving federal funding. The current Treasury proposal seeks to extend the logic of that ruling to the tax code, effectively codifying a federal standard that prohibits race-conscious financial aid and recruitment even at private institutions that do not receive direct federal grants.
Observers have noted that this represents an acceleration of federal scrutiny. While the Students for Fair Admissions ruling primarily concerned the Equal Protection Clause of the 14th Amendment and Title VI of the Civil Rights Act, the Treasury’s move leverages the "charitable purpose" doctrine of the tax code to achieve broader administrative compliance.
Analysis of Impact on Minority-Serving Institutions
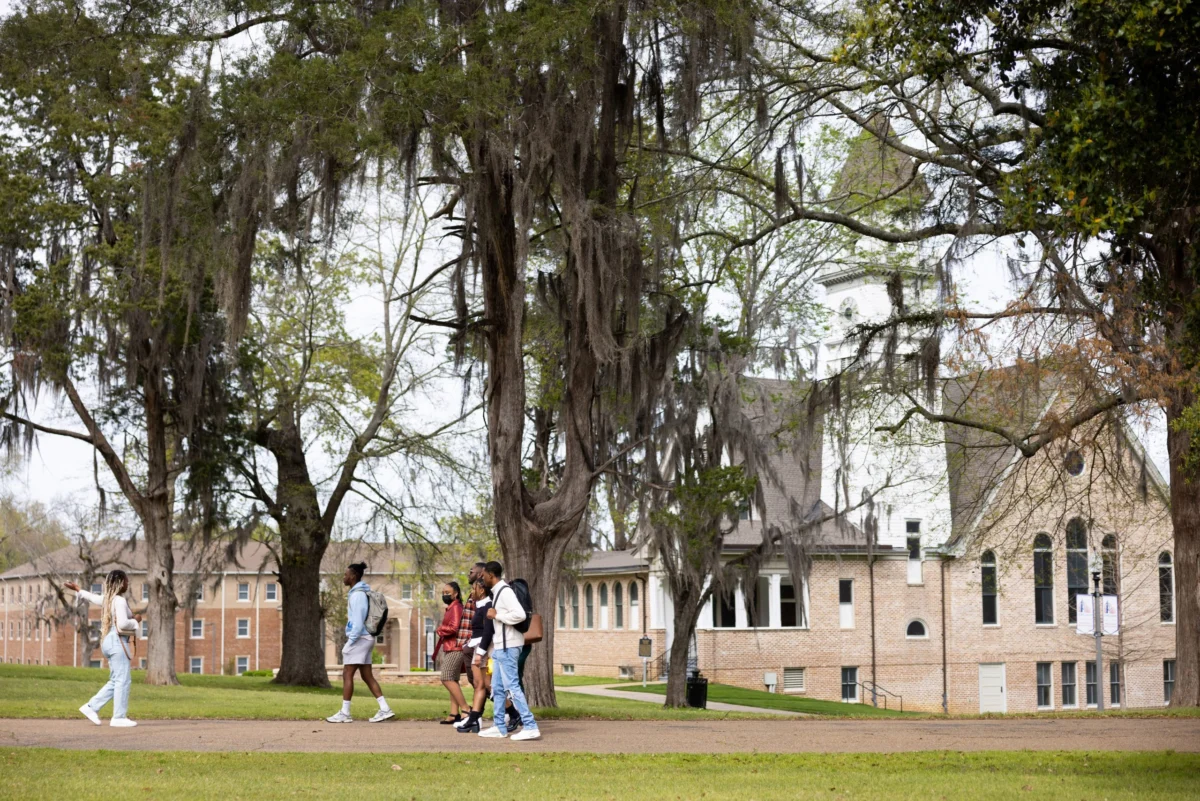
The institutions most likely to face existential threats under the new rule include Historically Black Colleges and Universities (HBCUs), Tribal Colleges and Universities (TCUs), and Hispanic-Serving Institutions (HSIs). These colleges were founded, in many cases, specifically to provide education to populations that were systematically barred from mainstream institutions.
For HBCUs, the use of race in scholarship programs is often tied to their foundational mission of uplifting communities that remain economically marginalized. Advocates argue that these programs are not exclusionary, but rather corrective. Data from the National Center for Education Statistics (NCES) indicates that minority-serving institutions enroll a significantly higher percentage of Pell Grant-eligible students than the national average. Critics of the Treasury proposal contend that by treating targeted scholarships as "discriminatory," the government risks dismantling the very mechanisms that have enabled first-generation and low-income students to access higher education.
The historical role of these institutions in providing a safe harbor for marginalized scholars is well-documented. During the early 20th century, when elite American universities maintained strict quotas against Jewish students and European scholars fleeing the rise of Nazi Germany, it was the HBCUs that opened their doors. Records from the Amistad Research Center show that at least 51 refugee scholars found faculty positions at 19 different HBCUs, demonstrating a legacy of intellectual inclusivity that persisted even when the rest of the American higher education system was actively practicing exclusion.
Economic and Educational Implications
The potential for widespread loss of tax-exempt status raises significant concerns regarding the broader economic health of the education sector. Small private colleges, which often operate on thin margins, are particularly vulnerable. According to the American Council on Education, many private, non-profit colleges have already faced a "demographic cliff" and increased inflationary pressures. The removal of tax-exempt status could act as a catalyst for a wave of institutional consolidations or closures.
From an educational perspective, the policy change could result in a decrease in student diversity. Research from the Lumina Foundation suggests that targeted financial aid is one of the most effective tools for increasing college completion rates among underrepresented demographics. If institutions are forced to abandon these programs to maintain their tax status, the unintended consequence may be a widening of the attainment gap between wealthy and low-income households.
Official Responses and Stakeholder Positions
The Treasury Department has stated that its goal is to provide clarity and consistency across the tax code. A spokesperson for the department indicated that the comment period for the proposal will remain open for 60 days, allowing for feedback from academic leaders, civil rights organizations, and the general public.
In contrast, organizations such as Complete College America have expressed deep concern. Leaders within the higher education community argue that the government is confusing "equality of opportunity" with "preferential treatment." They maintain that providing additional support, such as bridge programs or financial aid, to students who have faced historical barriers is a legitimate charitable activity that serves the public interest by ensuring a more educated and productive workforce.
Faith-based colleges have also expressed alarm. Many of these institutions utilize scholarships to support students who share their religious traditions, and they fear the new rule could be interpreted to encompass any criteria-based financial aid, potentially threatening the religious mission of these schools.
Future Outlook and Legal Challenges
As the regulatory process unfolds, legal experts anticipate a series of challenges. The central question will be whether the IRS has the administrative authority to define "discrimination" in a way that includes programs designed to broaden access for historically disadvantaged groups.
Constitutional scholars suggest that the proposal may face scrutiny under the First Amendment, particularly regarding the freedom of association and the right of private institutions to define their own missions. Furthermore, there is the potential for significant litigation if the Treasury proceeds to finalize the rules without substantial modifications to protect institutions that use race as a factor for the purpose of promoting diversity rather than exclusion.
For now, the higher education sector remains in a state of high alert. Colleges and universities are currently assessing their internal policies and endowment structures to determine how they might be impacted. The coming months will likely see intense lobbying and a flurry of legal filings, as institutions seek to balance the requirements of federal tax law with their commitments to expanding educational opportunity for all segments of the American population. Whether the proposal is ultimately implemented in its current form or significantly altered remains to be seen, but the debate has already served to highlight the fragile balance between national policy objectives and the independence of private academic institutions.




Leave a Reply