
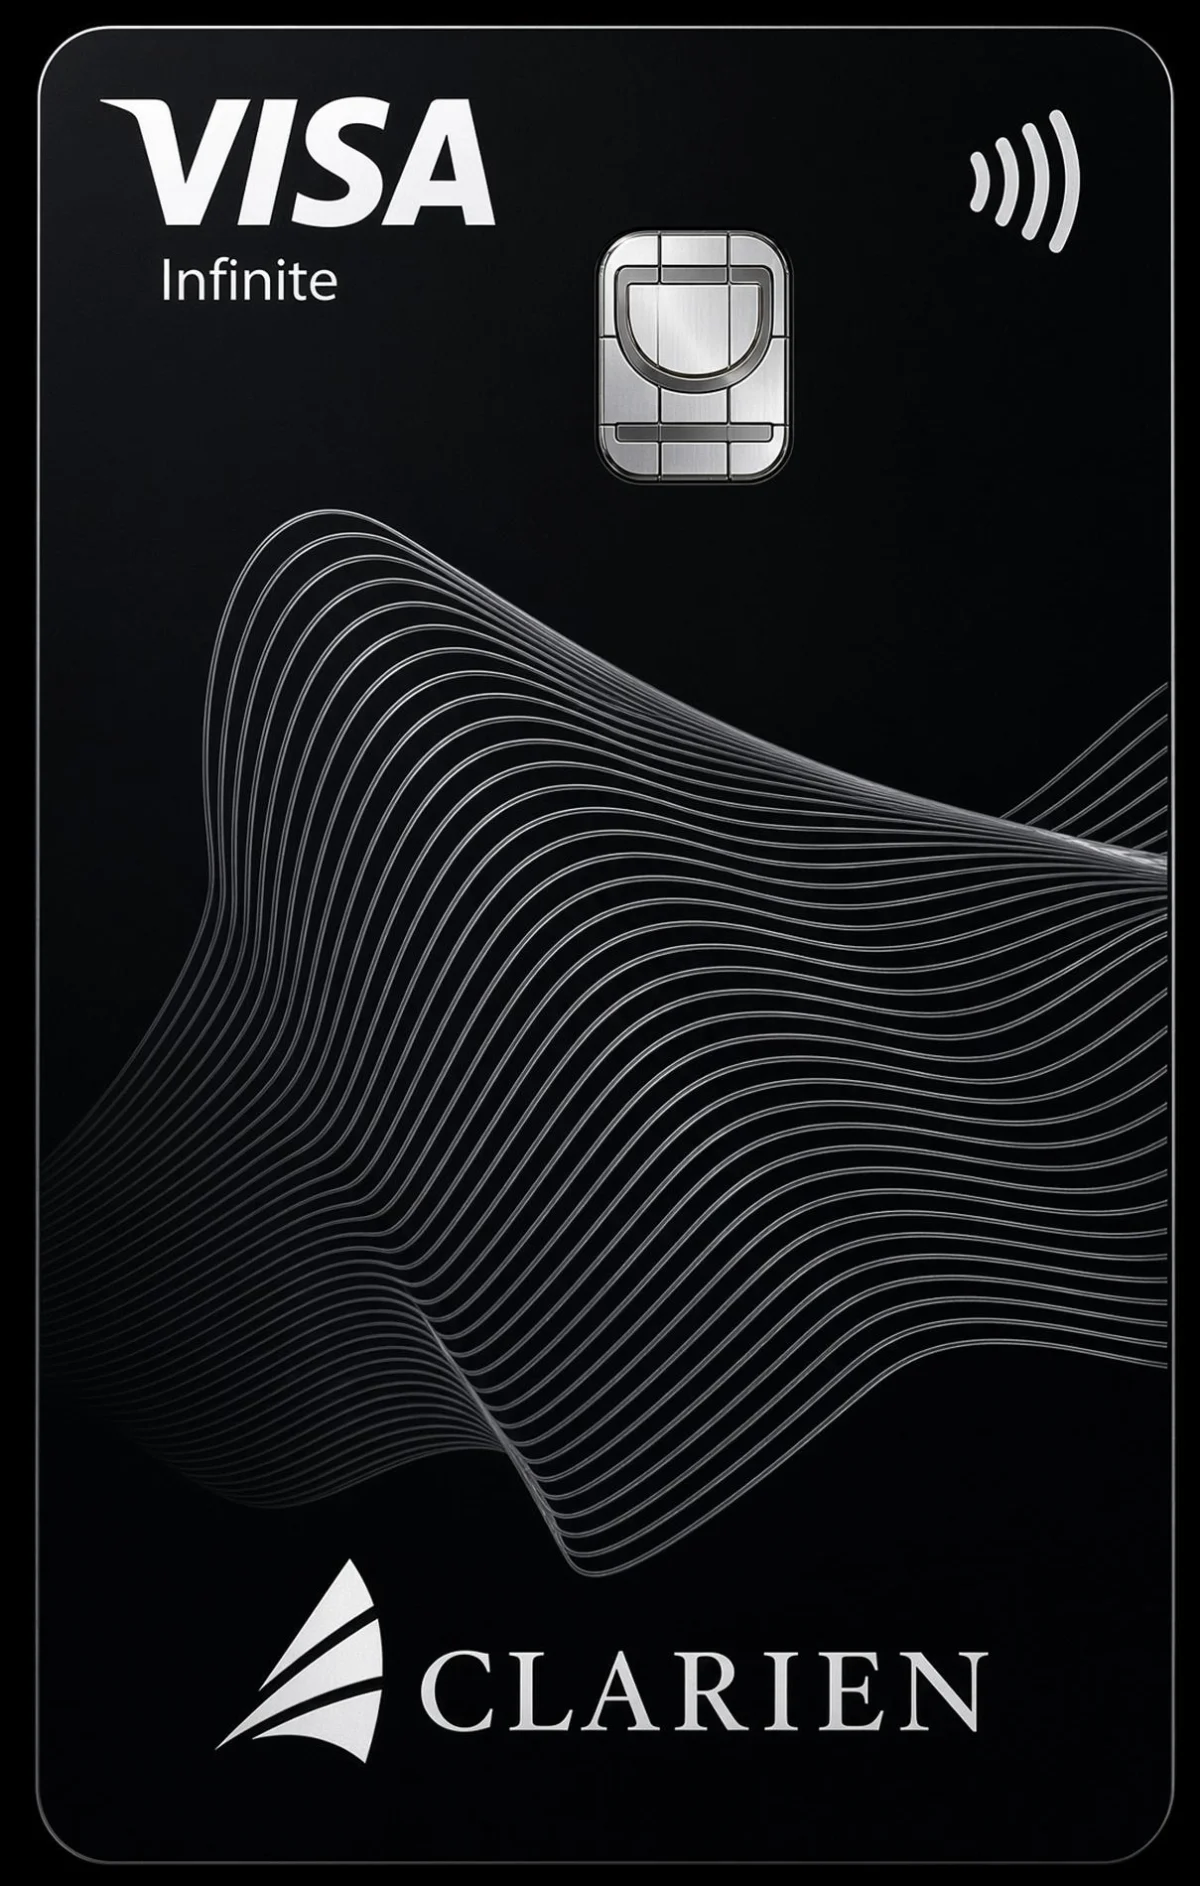
The phrase "Visa Infinite" once suggested the absolute zenith of consumer credit, evoking an image of boundless purchasing power and elite exclusivity. Logically speaking, very little should exist beyond infinity. However, the rapidly shifting landscape of ultra-high-net-worth consumer banking has forced global payment networks to redefine their own terminology. Today, Visa operates two distinct tiers above traditional Infinite cards in select global markets, signaling an aggressive arms race among credit card issuers to capture the world’s most affluent spenders.
While Visa has expanded upward with its "Infinite Privilege" and "Invitation-Only" "Infinite Private" tiers—primarily rolling them out across Canada, Asia, and Latin America—its chief competitor, Mastercard, has moved even faster in the United States. Mastercard has already introduced its own new top-tier designation, World Legend, bringing concrete, tangible benefits to U.S. consumers rather than relying on the vague promises of enhanced luxury often associated with older iterations of premium plastic.
This structural evolution of ultra-premium credit cards is not merely a branding exercise. It represents a fundamental shift in how payment networks, issuing banks, and merchants negotiate the economics of high-end consumer spending, driven largely by significantly higher merchant interchange fees.
A Brief History of the U.S. Infinite Market
To understand how the market arrived at these super-premium tiers, it is necessary to examine the introduction of the standard Visa Infinite product to the United States. Visa Infinite made its U.S. debut more than a decade ago, initially appearing on a very limited scale. In May 2015, financial observers noted the rollout of City National Bank’s Crystal Visa Infinite, which stood as one of the few commercially available U.S. Infinite cards at the time.
However, the category truly entered the mainstream consciousness in August 2016, when Chase launched the Sapphire Reserve. Alongside the Sapphire Reserve, Chase also upgraded its existing Ritz-Carlton credit card to the Visa Infinite tier. Crucially, the introduction of these cards coincided with Visa implementing higher interchange rates for Infinite-level products. These elevated merchant fees provided the necessary revenue stream to fund the rich reward structures, annual travel credits, and airport lounge access programs that immediately captivated affluent consumers.
Despite the early adoption in the U.S., the domestic market has remained anchored to the standard Infinite tier, missing out on the subsequent upward expansions seen in international jurisdictions.
The Canadian Pioneer: Infinite Privilege
While U.S. consumers became accustomed to the benefits of Sapphire Reserve and similar products, Canada quietly established a precedent for a higher tier of card benefits years earlier. The Visa Infinite Privilege tier can be traced back to the 2013–2014 rollout of the TD Aeroplan Visa Infinite Privilege card, meaning Canadian consumers were utilizing ultra-premium banking products long before Americans began clamoring for modern travel rewards cards.
Today, the Infinite Privilege card is ubiquitous across the Canadian banking landscape, offered by major institutions like Royal Bank of Canada (RBC), which provides products such as the Avion Visa Infinite Privilege for Private Banking.
The value proposition of the Canadian Infinite Privilege tier extends far beyond standard point multipliers. Cardholders frequently enjoy tangible, time-saving airport benefits, including dedicated fast-track security lanes at major Canadian transportation hubs such as Vancouver, Montreal, Ottawa, and Billy Bishop Toronto City airports. Furthermore, these cards bundle elite parking privileges and enhanced hotel amenities through proprietary hotel partnership programs, establishing a clear functional gap between standard Infinite and Infinite Privilege offerings.
Expanding into Asia: The Rise of Infinite Private
The international footprint of these ultra-premium tiers expanded dramatically on July 16, 2026, when Visa officially announced its refreshed Asia Pacific Infinite lineup. In a landmark multi-market rollout, United Overseas Bank (UOB) partnered with Visa to launch the new Visa Infinite Privilege and Visa Infinite Private tiers across Singapore, Malaysia, Thailand, Indonesia, and Vietnam. This strategic move transitioned more than 300,000 existing Infinite cardholders into these newly established upper tiers.

The distinction between standard Visa Infinite and Visa Infinite Privilege in the Asian market is highlighted by a stark upgrade in travel and lifestyle perks. For instance, while a standard Visa Infinite cardholder might receive a 50% discount on DragonPass airport fast-track services, an Infinite Privilege cardholder receives two complimentary passes annually. Similarly, hotel partnerships reflect this hierarchy: standard cardholders gain a six-month membership to the ALL Accor+ Explorer program, whereas Privilege cardholders enjoy a full 12-month membership. Furthermore, the newly minted "Infinite Private" tier takes exclusivity to an entirely different level. Described by Visa as strictly invitation-only, this tier pairs higher credit limits with a dedicated human concierge capable of anticipating complex client requests, such as securing private after-hours access to exclusive art galleries and social clubs.
Strategic partnerships have also been customized for these upper tiers. A notable merchant-funded offer in collaboration with the Banyan Group grants Privilege and Private cardholders accelerated Voyager status and access to an exclusive collection of luxury complimentary stays—such as a Bliss Pool Villa at Banyan Tree Mayakoba—while ordinary Infinite cardholders are restricted to lower-tier Explorer status fast-tracks and more limited hotel selections.
Mastercard Fired the First U.S. Salvo with World Legend
While U.S. consumers have been largely shielded from Visa’s newest tiers, Mastercard took a decisive lead in the domestic ultra-premium market by introducing the World Legend tier last summer, sitting comfortably above World Elite. Along with this new tier, Mastercard launched "The Mastercard Collection," a cohesive benefits program spanning multiple World designations.
The World Legend card brings concrete, high-value perks directly to U.S. consumers. Among the most notable benefits is complimentary access to "Taste by Priceless" airport dining spaces. Located in major global hubs such as Hong Kong—conveniently situated near Gate 41 adjacent to the former Chase Sapphire Lounge space—and São Paulo, these dedicated dining venues offer chef-designed menus and specialized beverage programs for the cardholder and up to three guests, subject to capacity.
In addition to fine-dining airport experiences, Mastercard’s World Legend package includes prebooked security fast-track access at participating international airports outside the United States. It also extends lifestyle benefits such as a complimentary Soho Friends account paired with a $100 credit toward a Soho House bedroom stay, directly targeting the cultural and lifestyle preferences of modern affluent travelers.
The Economic Engine: Higher Interchange Fees
The proliferation of these ultra-premium credit card tiers is fundamentally anchored in the economics of payment processing. Issuing banks do not provide concierge services, luxury hotel statuses, and extensive airport lounge networks out of charity; these perks are heavily subsidized by elevated merchant interchange fees.
An examination of Visa’s Canadian domestic interchange schedule illustrates this financial mechanism clearly. Within the standard consumer credit tables, the electronic interchange rate for a standard Visa Infinite transaction sits at approximately 1.57%. By comparison, the electronic interchange rate for a Visa Infinite Privilege transaction jumps to 2.08%. For card-not-present transactions—typically online or keyed-in purchases—the disparity widens even further, moving from 1.65% for standard Infinite to 2.40% for Infinite Privilege.
These percentages represent revenue collected by the issuing bank to offset the cost of the rewards and benefits package, with total merchant processing costs further compounded by third-party processor fees. As banks continue to court high-net-worth individuals with increasingly lavish perks, merchants across all retail and hospitality sectors continue to shoulder the escalating cost of processing transactions on these ultra-exclusive cards.
Market Implications and Future Outlook
The introduction of tiers like Visa Infinite Privilege, Visa Infinite Private, and Mastercard World Legend marks a definitive turning point in the consumer credit industry. The traditional stratification of Classic, Gold, Platinum, and Infinite has proven insufficient for an expanding global class of ultra-wealthy consumers who demand hyper-personalized service and tangible lifestyle integration.
For international travelers, particularly in Canada and Asia, these super-premium cards have become standard tools for navigating high-end travel seamlessly. Meanwhile, the pressure is mounting on U.S. issuers to eventually introduce Visa’s higher tiers domestically to counter Mastercard’s aggressive World Legend foothold. As the boundary between financial services and luxury concierge lifestyle management continues to blur, the ultimate question for the industry will be how much higher interchange fees can climb before merchants—and regulators—push back against the true cost of infinite luxury.




Leave a Reply