
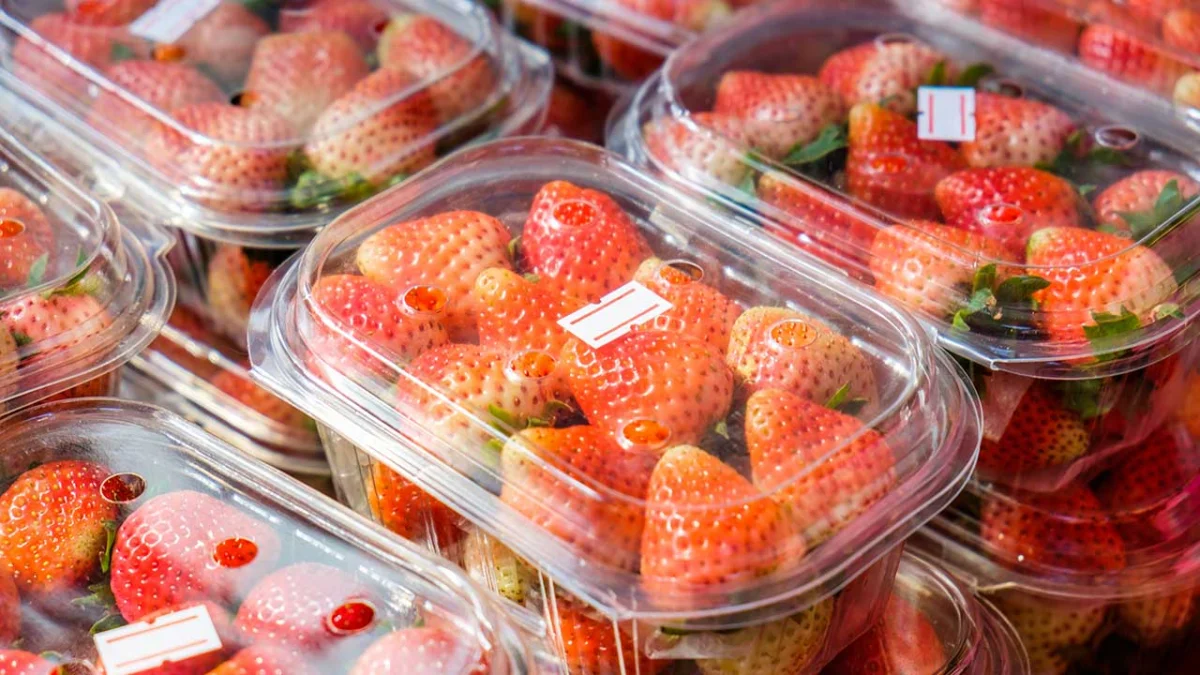
By 2028, the mundane act of grocery shopping will undergo a quiet but radical transformation. The produce section will lose its sea of plastic clamshells in favor of fiber-based punnets; microwaveable meals will shed their opaque black plastic trays for clear, recyclable alternatives; and online deliveries will arrive swaddled in paper rather than plastic air pillows. These changes, while seemingly aesthetic, are the tangible manifestations of California’s Senate Bill 54 (SB 54), the Plastic Pollution Producer Responsibility Act. Signed into law in 2022 and moving through its critical regulatory phases as of May 2026, the legislation represents the most aggressive attempt in the United States to dismantle the throwaway culture that has dominated consumer markets for decades.
The scope of this law extends far beyond the borders of the Golden State. Because multinational corporations rarely maintain separate supply chains for different geographic regions, the rigorous requirements set by California are effectively functioning as a national standard. As manufacturers scramble to comply with California’s mandates to avoid logistical fragmentation, the American consumer—regardless of their home state—is witnessing a permanent shift in how products are packaged, distributed, and disposed of.
The Anatomy of the Waste Crisis
To grasp the necessity of SB 54, one must confront the sheer scale of plastic proliferation. In 1960, plastic accounted for a negligible 0.4% of the municipal solid waste stream in the United States. By 2018, that figure had ballooned to 12.2%, according to EPA data. Packaging is the primary driver of this trend; approximately 36% of all manufactured plastic is destined for single-use containers, with a staggering 85% of that material ultimately finding its way into landfills rather than recycling facilities.
SB 54 seeks to reverse this trajectory through the mechanism of Extended Producer Responsibility (EPR). By shifting the financial burden of waste management from the taxpayer to the producer, the law creates a direct fiscal incentive for companies to reduce packaging volume and improve the recyclability of their materials. If a company continues to use "problematic" or "hard-to-recycle" materials, they will face escalating fees, a cost-prohibitive penalty designed to force innovation.
A Chronology of Compliance
The implementation of SB 54 is structured as a multi-year transition, providing a clear roadmap for producers, retailers, and consumers alike:
- May 2026: The finalized regulations officially took effect. Producers were required to register with the Circular Action Alliance or opt for independent compliance plans, marking the beginning of the formal accountability era.
- January 2027: The program moves into full implementation. Producers must ensure that their single-use plastic packaging is at least 10% lower than the 2023 baseline. Any producer failing to meet these standards or failing to register is legally barred from selling covered materials within California.
- January 2028: The threshold for actual recycling—not just theoretical recyclability—increases to 30%. This forces manufacturers to move away from materials like black plastic, which modern optical sorters cannot identify.
- January 2030: The recycling mandate climbs to 40%, accompanied by a 20% reduction in total source material. This stage is expected to normalize refillable container systems and concentrated product pods.
- January 2032: The final, ambitious deadline arrives. All covered packaging must be 100% recyclable or compostable, with a total source reduction of 25% and a recycling rate of 65%.
Targeted Materials and Industrial Shifts
The law specifically targets "problematic" packaging that has historically undermined recycling efforts. Expanded Polystyrene (EPS), commonly known as Styrofoam, is the first casualty. Because it is largely composed of air and breaks into microplastics, it is expensive to transport and impossible to recover cleanly. With the ban on EPS food service ware now in effect, the market is pivoting toward molded fiber, paper-based clamshells, and sustainable alternatives that do not carry the health risks associated with styrene exposure.
Similarly, the ubiquitous "black plastic" tray is being phased out. Modern near-infrared (NIR) sorters in recycling centers utilize light to identify plastic types; however, the carbon black pigment used in these trays absorbs the light, rendering the material invisible to sorting machinery. The industry is responding by shifting toward clear or light-colored polyethylene terephthalate (PET), which is highly valued in the circular economy and easily processed by existing sorting infrastructure.
Polyvinyl chloride (PVC) is also under fire. Often used for blister packs and clear clamshells, PVC is a "contaminant" that ruins entire bales of recyclable PET. Its removal from the packaging stream is essential for increasing the quality of recovered materials. Finally, "oxo-degradable" plastics—materials that merely fragment into microplastics rather than breaking down into organic matter—are being pushed out under the law’s stringent anti-greenwashing provisions.
The Conflict: Litigation and Industry Pushback
The path to 2032 is not without controversy. In June 2026, a coalition of environmental groups—including Oceana, the Natural Resources Defense Council (NRDC), and the Californians Against Waste Foundation—filed suit in the San Francisco Superior Court. The plaintiffs argue that the regulatory framework established by the state contains too many "loopholes," specifically regarding exemptions for certain plastic categories and the potential for companies to claim indefinite delays.
These groups contend that if the regulations are not tightened, the law may fail to achieve the intended reduction in microplastic pollution. Conversely, industry lobbyists argue that the timelines are aggressive and that the lack of federal coordination creates an uneven playing field. Despite this legal tension, the movement toward EPR is gaining momentum globally, with states like Colorado, Maine, Oregon, and New York adopting or considering similar frameworks. This "patchwork" of state-level policy is ironically forcing a national harmonization; to avoid navigating fifty different sets of regulations, major brands are choosing to adopt the California standard as their baseline.
Implications for the Consumer
For the average shopper, the next six years will be characterized by a noticeable change in texture and disposal. The "confusion factor"—standing in front of a recycling bin wondering if a container is actually recyclable—is the primary problem the law aims to solve. As standardized labeling becomes mandatory, the reliance on third-party certifications like the Biodegradable Products Institute (BPI) logo for compostables and the How2Recycle system for recyclables will increase.
However, consumers must remain vigilant against "greenwashing." The rise of "bioplastics" presents a new challenge. While these materials are derived from renewable resources, they often require commercial composting facilities to break down. If tossed into a standard landfill, they behave like traditional plastic. Furthermore, some studies suggest that certain compostable bags may contain high levels of chemical additives, complicating the narrative that "plant-based" is inherently benign.
Toward a Circular Economy
The long-term vision of SB 54 is a circular economy where waste is designed out of the system at the manufacturing stage. The EPR fees collected from producers are not simply taxes; they are investments. These funds are earmarked for the modernization of Material Recovery Facilities (MRFs), enabling the installation of advanced robotics and AI-driven sorting technology that can handle complex packaging types.
If the 65% recycling rate is achieved by 2032, it will represent a historic shift in resource management. For the consumer, this will likely manifest as a return to more sustainable shopping habits: bulk refills for household cleaners, a shift toward stainless steel or glass containers for deli items, and a reduction in the "over-packaging" that currently defines online retail.
While the legal battles and regulatory debates will continue in the coming years, the direction of the market is clear. The era of cheap, disposable, and invisible plastic waste is reaching its expiration date. As California sets the stage, the rest of the country is finding itself in the wings, preparing for a transition that will redefine the relationship between the products we consume and the environment we occupy. The success of this law will not be measured by the number of lawsuits filed or the complexity of the regulations, but by the tangible reduction of waste entering our landfills and the degree to which sustainability becomes the default, rather than the alternative.




Leave a Reply