
The international aviation sector is undergoing a period of significant strategic realignment, highlighted by major adjustments to route networks, long-haul fleet investments, and updated bilateral air services agreements. As airlines prepare for shifts in seasonal demand and ultra-long-haul operations, key industry players are redefining connectivity between Australia, Asia, North America, and the Middle East. These developments are reshaping market competition, altering pricing strategies, and influencing capacity across major global corridors.

Network Adjustments and Route Rationalizations
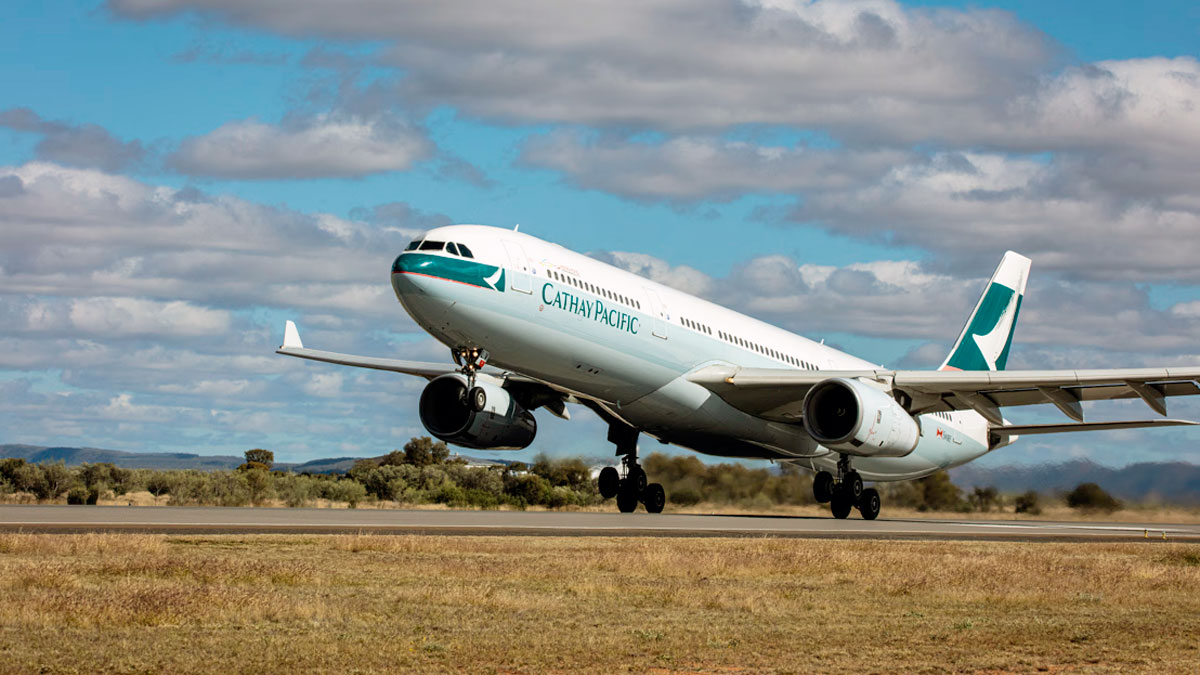
A notable development in the Asia-Pacific region involves Cathay Pacific’s decision to permanently discontinue its seasonal direct flights between Cairns and Hong Kong. The route, which historically operated three times weekly during the peak December-to-February holiday period, served as a vital direct link connecting Tropical North Queensland to Cathay Pacific’s primary hub at Hong Kong International Airport.
According to carrier representatives, the suspension of the seasonal service is a commercial decision driven by fleet allocation strategies and shifting regional demand patterns. While the removal of the Cairns-Hong Kong service temporarily reduces direct international access for North Queensland travelers, the airline maintains that regional passengers can still connect to its network through major Australian gateways such as Sydney, Melbourne, Brisbane, and Perth. Industry analysts note that carriers are increasingly rationalizing secondary routes to concentrate capacity on high-density trunk routes where yields are stronger and aircraft utilization can be maximized.
Conversely, capacity between Australia and Indonesia is poised for substantial expansion following the recent modernization of bilateral air services arrangements. For the first time in 15 years, both governments have updated their bilateral aviation treaty, unlocking an additional 5,000 weekly airline seats for carriers operating between the two nations. Beyond expanding capacity on traditional trunk routes connecting major Australian capitals to Denpasar (Bali) and Jakarta, the modernized framework grants airlines greater regulatory flexibility to serve emerging secondary destinations within Indonesia. Aviation economists anticipate that this expanded framework will intensify competition among low-cost and full-service carriers, potentially driving down average airfares and stimulating leisure and business travel demand across the corridor.
Fleet Innovations and Ultra-Long-Haul Projections
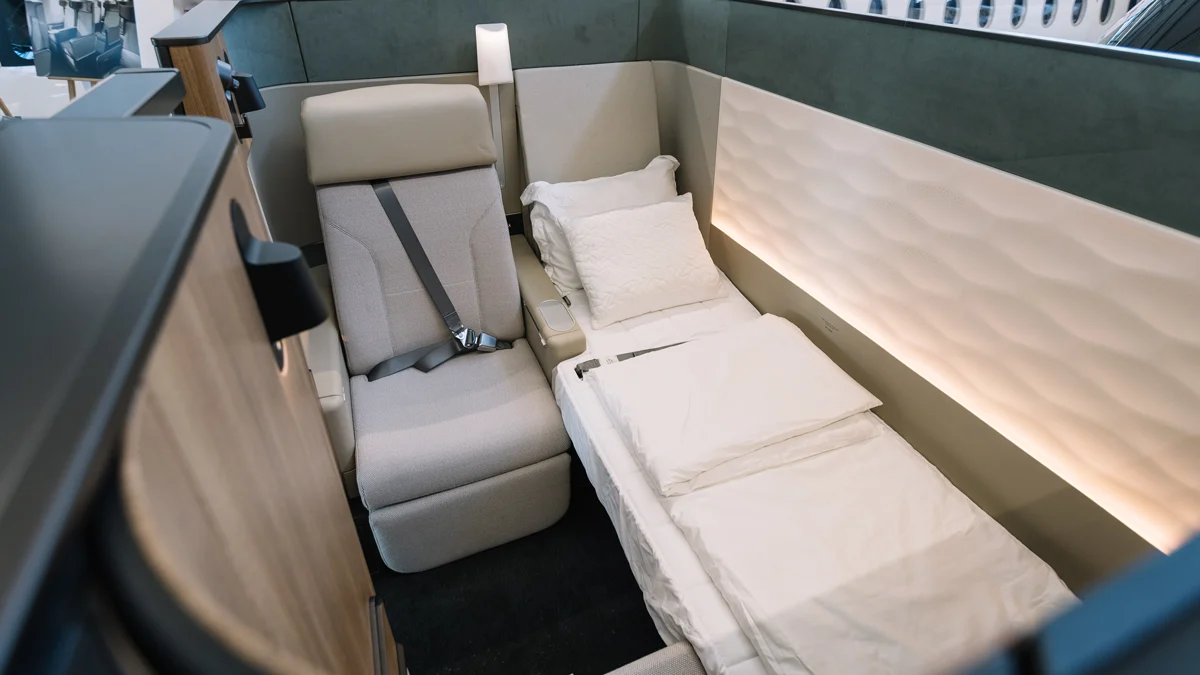
In the ultra-long-haul sector, Qantas continues to advance preparations for its highly anticipated "Project Sunrise" non-stop services linking Australia’s east coast to global financial capitals such as New York and London. Central to this strategy is the introduction of specialized Airbus A350-1000ULR (Ultra Long Range) aircraft, which will feature a redesigned, low-density cabin layout intended to enhance passenger comfort on journeys exceeding 20 hours.

Industry observers and aviation analysts have debated the commercial viability of the ultra-premium pricing model anticipated for these flights. Qantas executives are reportedly betting that the unprecedented convenience of non-stop travel, combined with state-of-the-art First Class suites equipped with separate sit-down armchairs and full-length flat beds, will command a revenue premium of 20% to 40% over traditional one-stop connecting itineraries.
While luxury-focused travelers and corporate accounts are expected to drive robust initial demand, aviation strategists emphasize that the financial success of Project Sunrise will depend heavily on sustained corporate yield growth and the operational efficiency of the A350-1000ULR airframe. The introduction of these suites sets a new benchmark for ultra-long-haul commercial aviation, prompting competing carriers to reevaluate their own flagship cabin products.

Regional Connectivity and Code-Share Expansions
The broader competitive landscape is further defined by a series of network enhancements announced by international carriers operating into the Australian market. Qatar Airways has confirmed plans to increase frequencies on its primary Australian routes starting in December, reinforcing Doha’s position as a major connecting hub for European and African traffic. Similarly, TransNusa is scheduled to launch new low-cost services between Melbourne and Bali in October, introducing competitive economy fare structures starting at AU$299 to capture budget-conscious leisure travelers.
Air New Zealand has also leveraged seasonal promotional campaigns, including its "SaleAway" fare specials targeting trans-Tasman routes, to stimulate demand during the shoulder travel period. Meanwhile, Chinese carrier Shenzhen Airlines is scheduled to inaugurate a four-weekly service connecting Sydney to Shenzhen this December, further restoring pre-pandemic capacity levels between Australia and mainland China.
The operational expansion of Canadian carriers highlights North America’s ongoing aviation recovery. Recent evaluations of Air Canada’s transcontinental operations, such as the introduction of Airbus A321-200 and A330-200 aircraft equipped with modern business-class configurations on routes between Vancouver and Ottawa, reflect a broader industry trend toward narrowbody deployment on domestic and regional thin-trunk routes to optimize fuel burn and operational flexibility.
Macroeconomic Implications and Consumer Outlook
As the global airline industry navigates these structural changes, passengers face a complex operational environment characterized by fluctuating ticket prices, shifting route maps, and evolving onboard product offerings. Travel industry associations advise international travelers to review comprehensive documentation requirements, verify up-to-date health and vaccination mandates, and ensure travel insurance policies adequately cover potential disruptions.

The consolidation of secondary routes by legacy carriers, contrasted with the rapid expansion of low-cost capacity in leisure-heavy markets like Indonesia, underscores a bifurcated market strategy. Full-service airlines are increasingly focusing on premium yields and ultra-long-haul differentiation, while low-cost operators capitalize on high-volume, point-to-point regional demand. As these trends mature through the upcoming travel seasons, the global aviation market will continue to reflect both the resilience of international travel demand and the economic imperatives driving modern airline network planning.




Leave a Reply